Insights

Performance reports and market commentary

Monthly results with the trader’s comment, market notes and risk analysis from the Algotoria investment team.

2026
Performance reports

Monthly report: September 2026 and third quarter

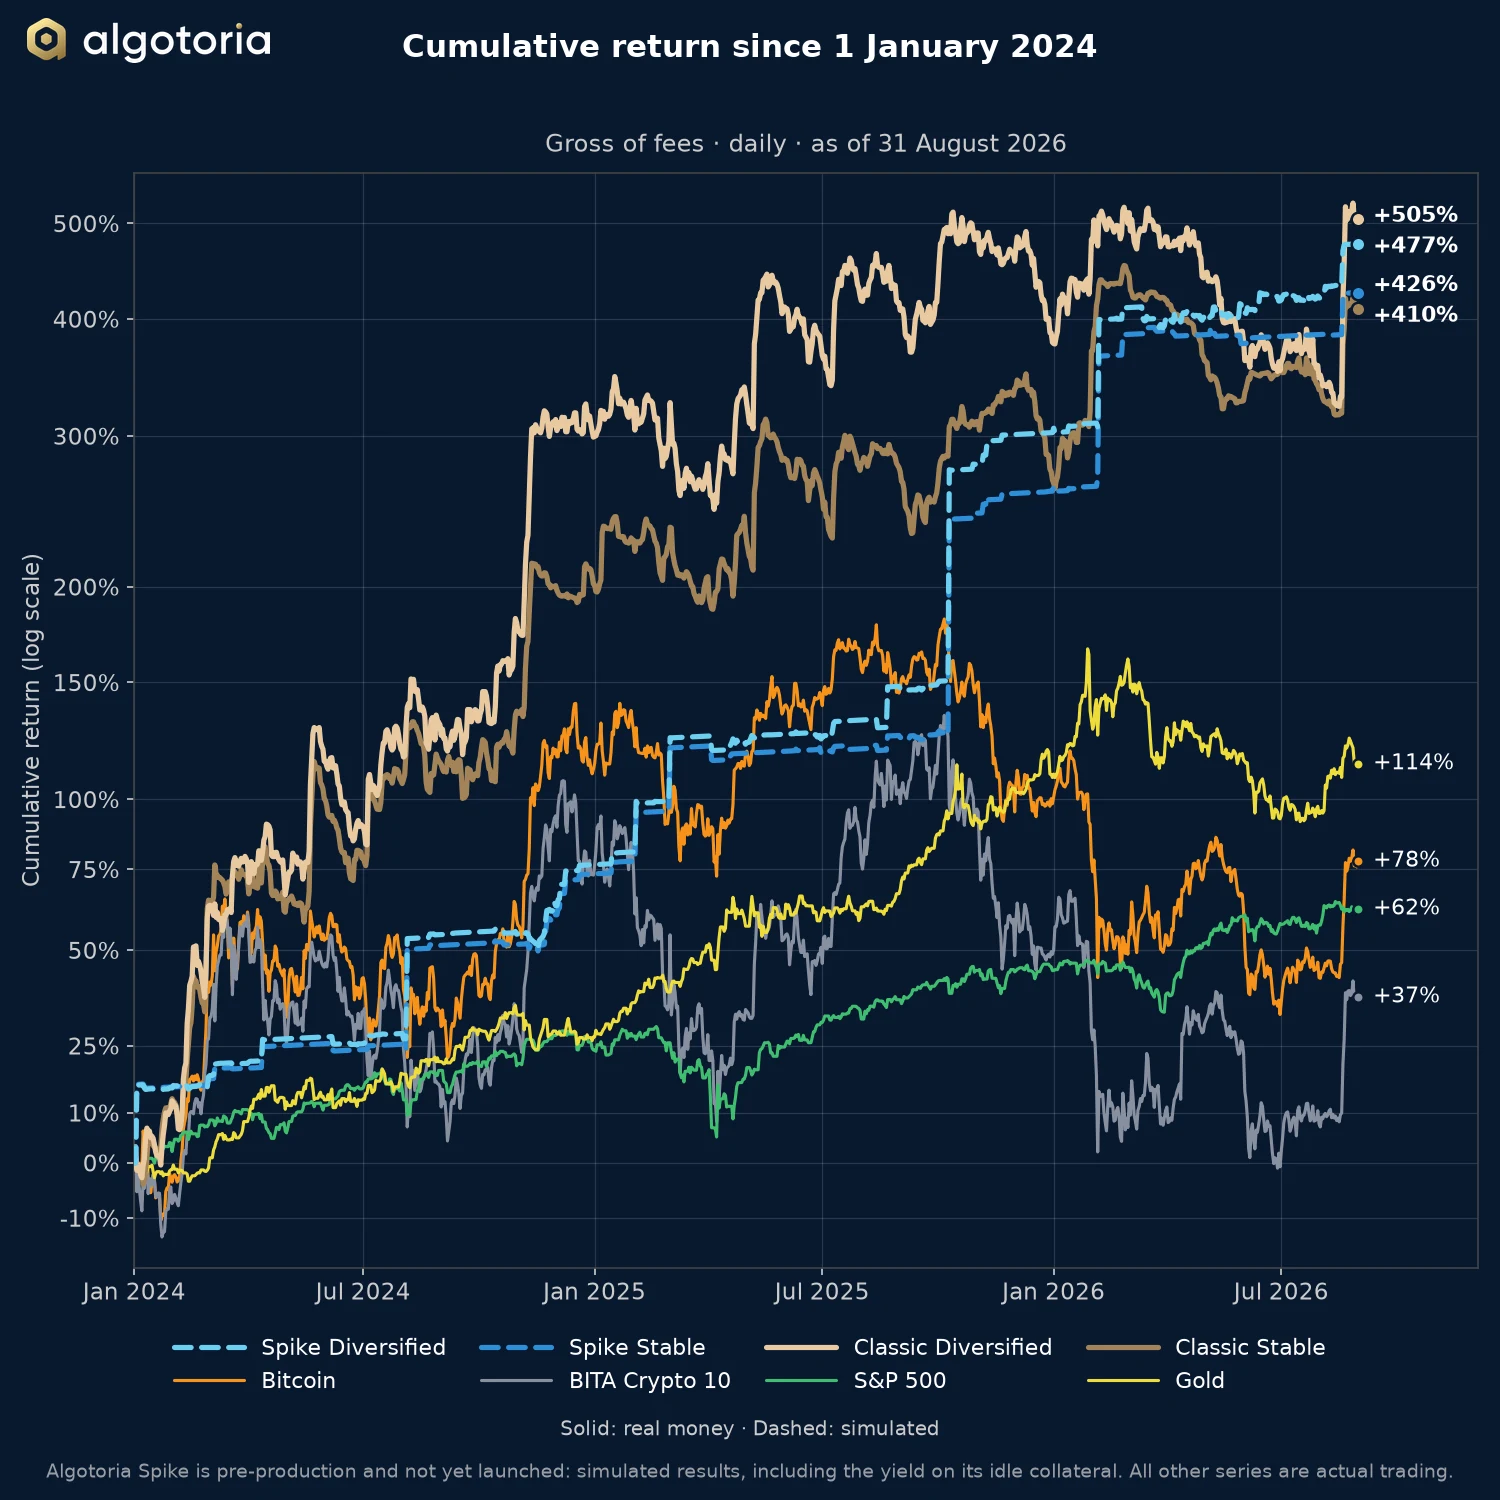
Classic Diversified returned +35.46% and Classic Stable +10.40% in the third quarter of 2026, after a flat July, a strong August and a choppy September.

Read →
Performance reports

Monthly report: August 2026

Classic Diversified returned +35.40% in August 2026 and Classic Stable +16.68%, as the market broke out of a long period of low volatility.

Read →
Strategy and risk

Why trend-following strategies go through flat periods

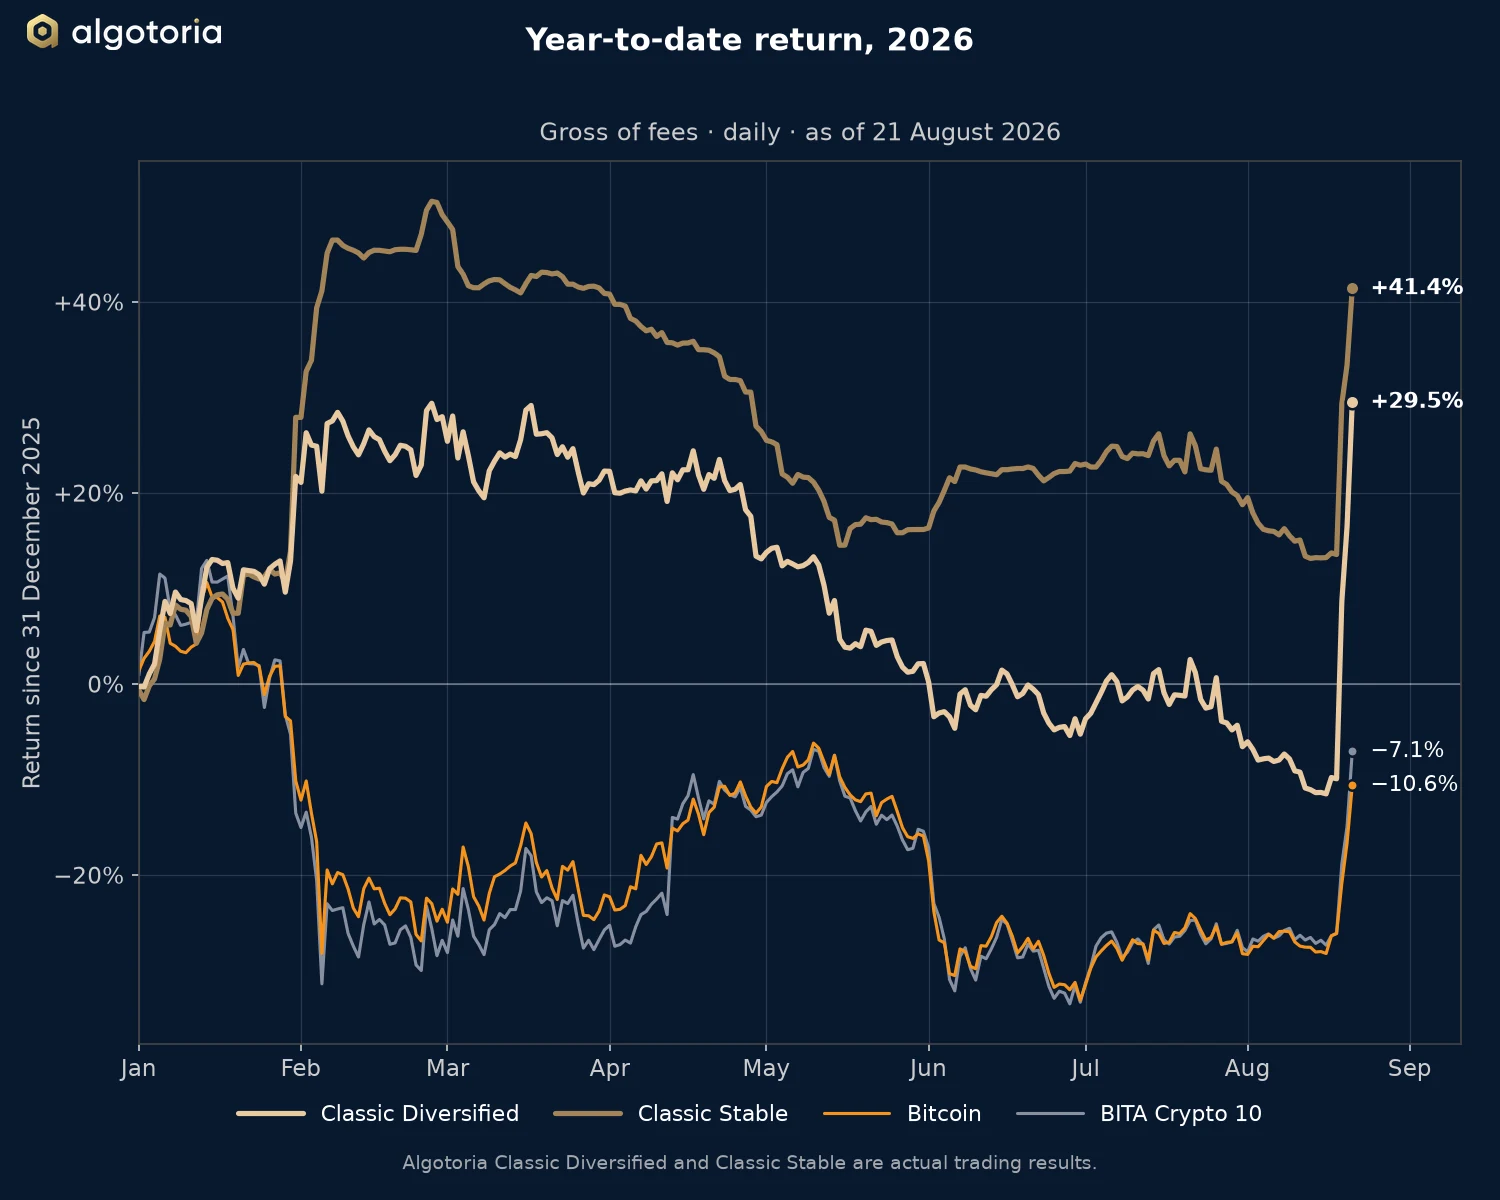
After a strong start to 2026, trend-following gave back gains in a long sideways market. In the seven days to 21 August Classic Diversified returned +46.14%.

Read →
Market commentary

The 19 August 2026 breakout

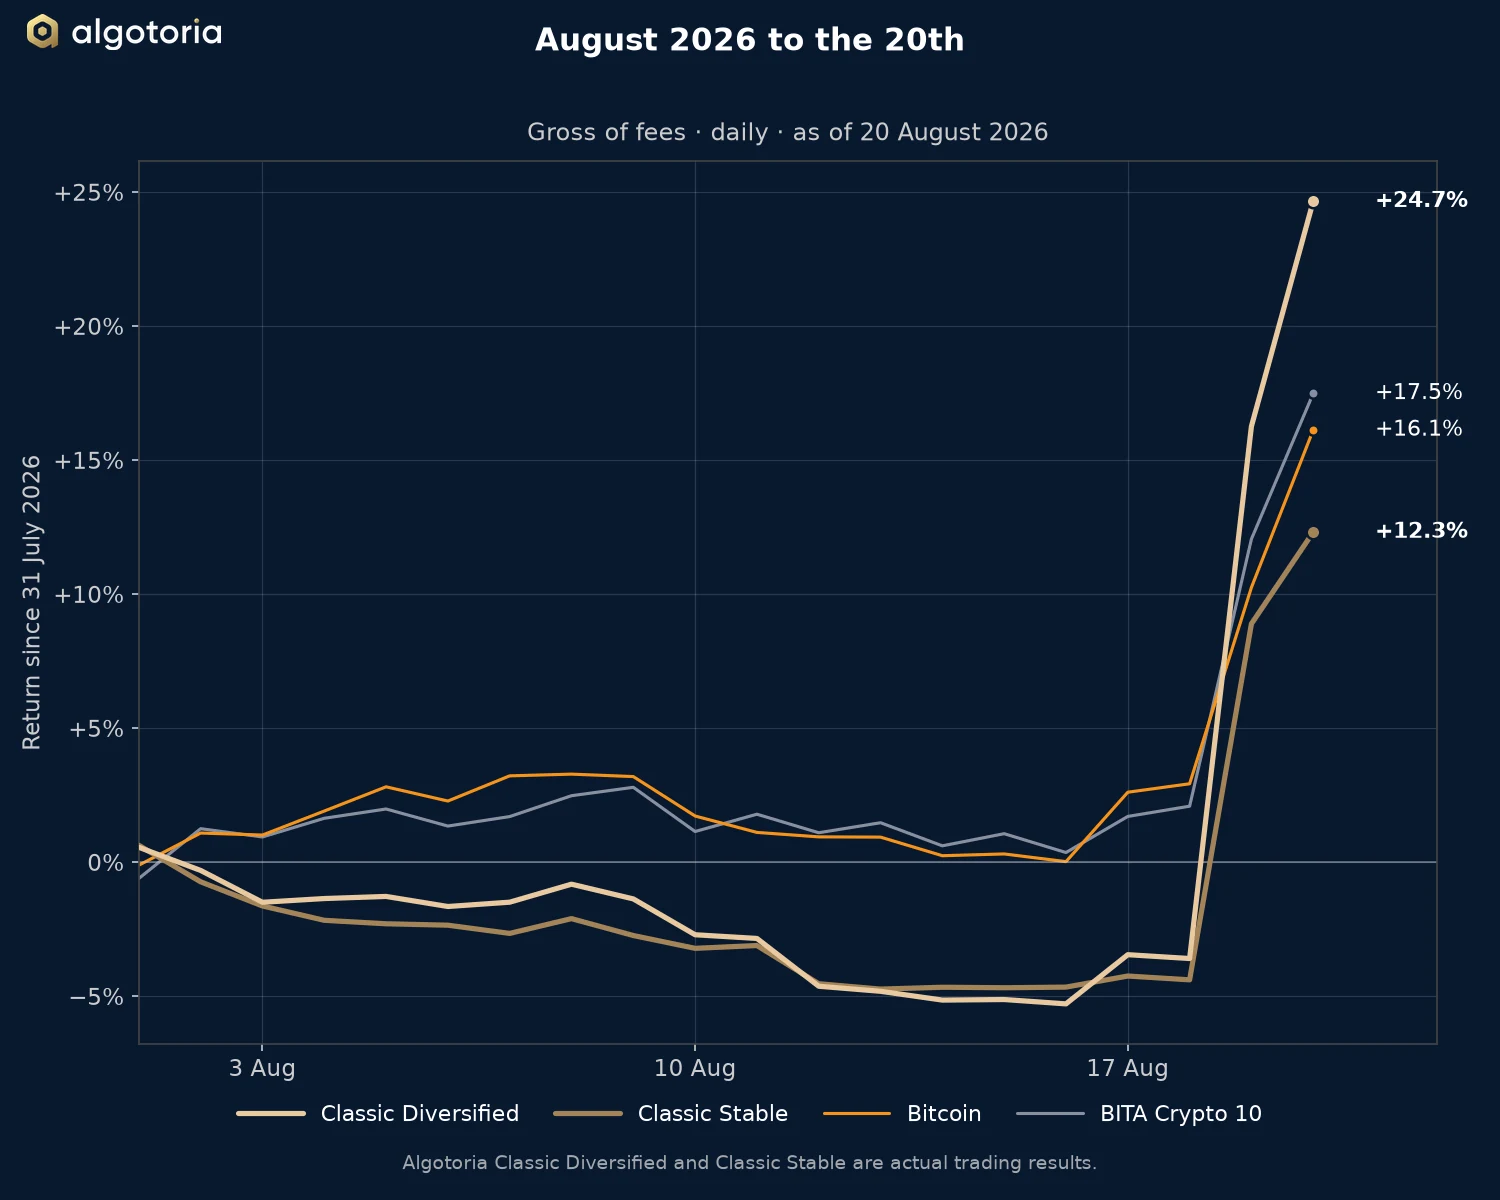
On 19 August 2026 the market broke out of a months-long range. Classic Diversified returned +20.59% on the day and Classic Stable +13.89%.

Read →
Performance reports

Monthly report: July 2026

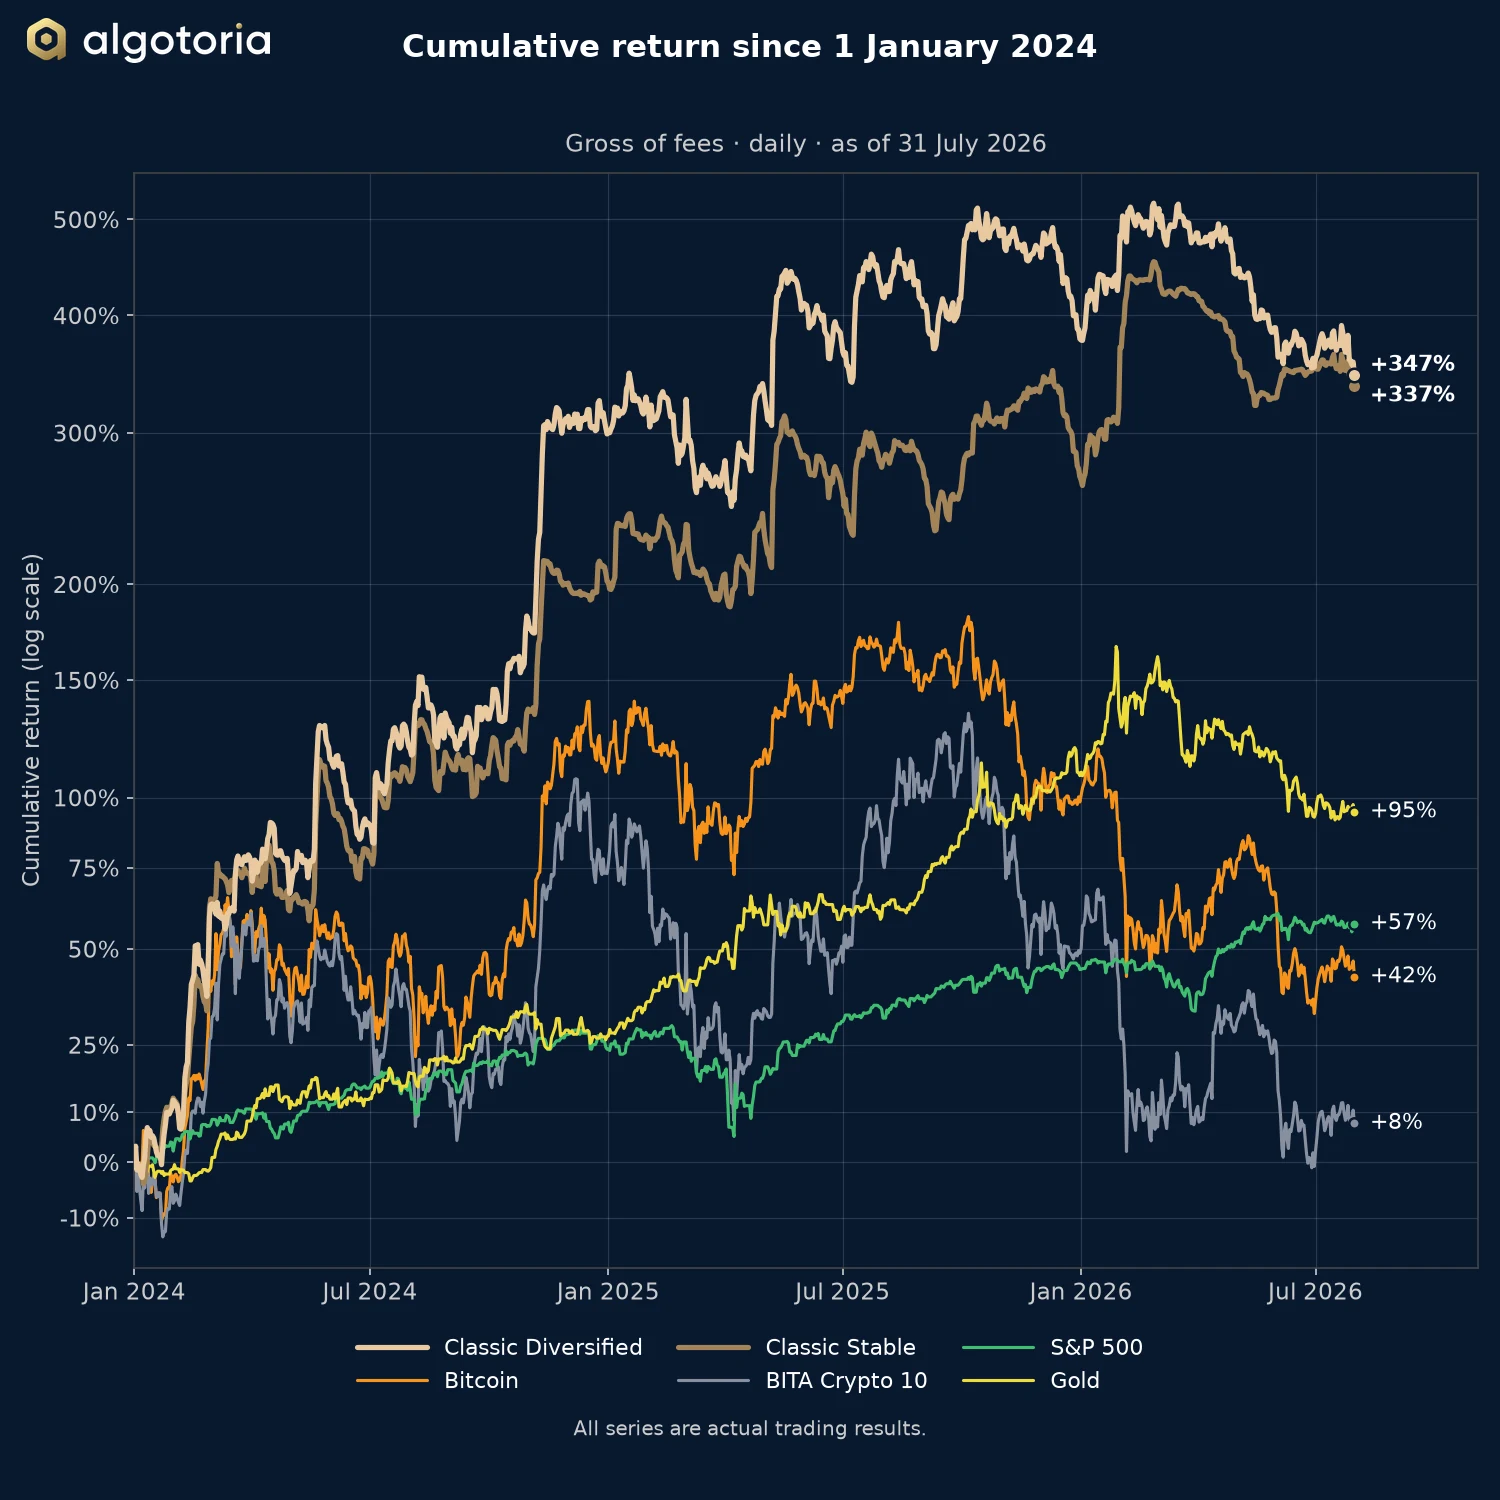
Classic Diversified returned −1.39% in July 2026 and Classic Stable −3.36%, in a market without a sustained trend. The comment sets this against the longer record.

Read →
Performance reports

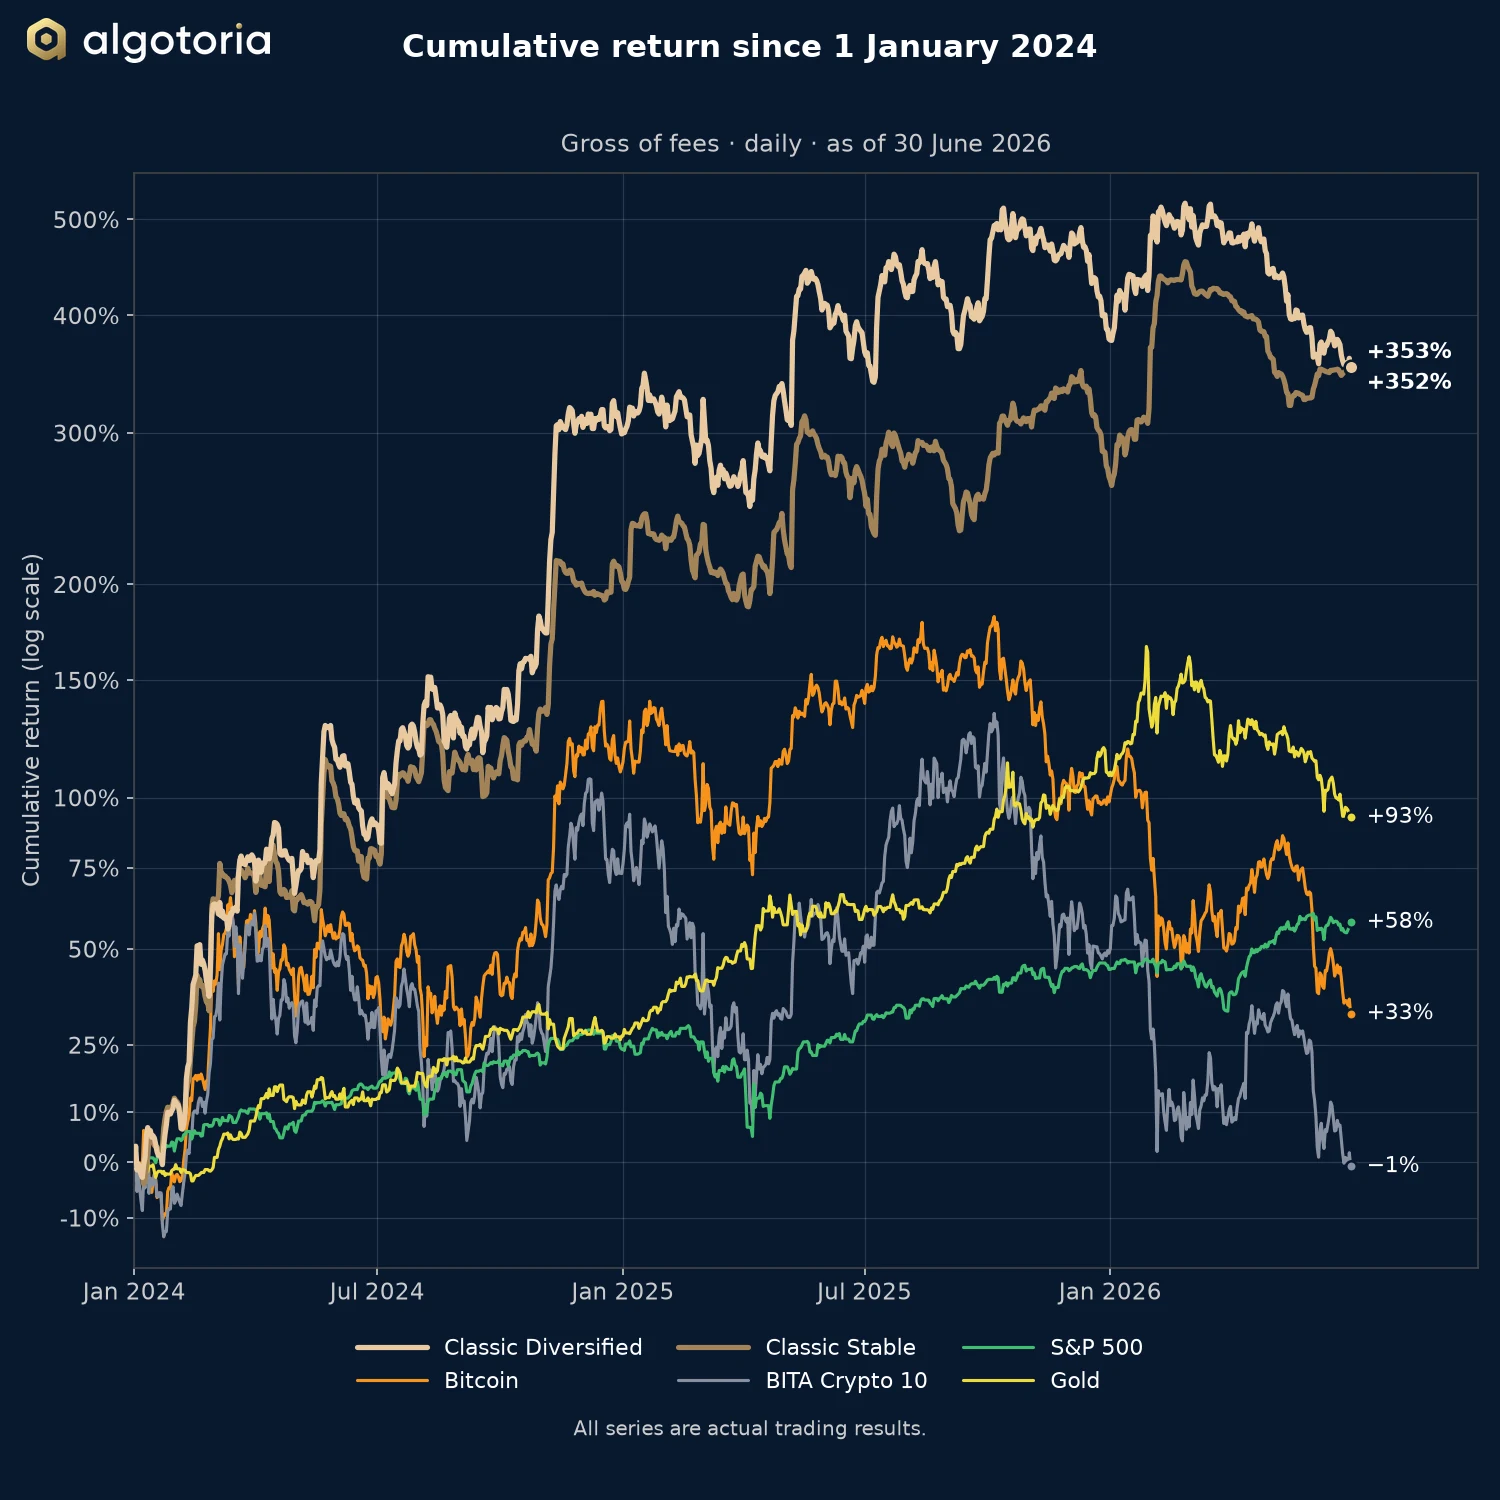
Monthly report: June 2026

Classic Stable returned +5.79% in June 2026 and Classic Diversified −7.24%, while Bitcoin fell. The comment explains how the shape of a move decides the result.

Read →
Performance reports

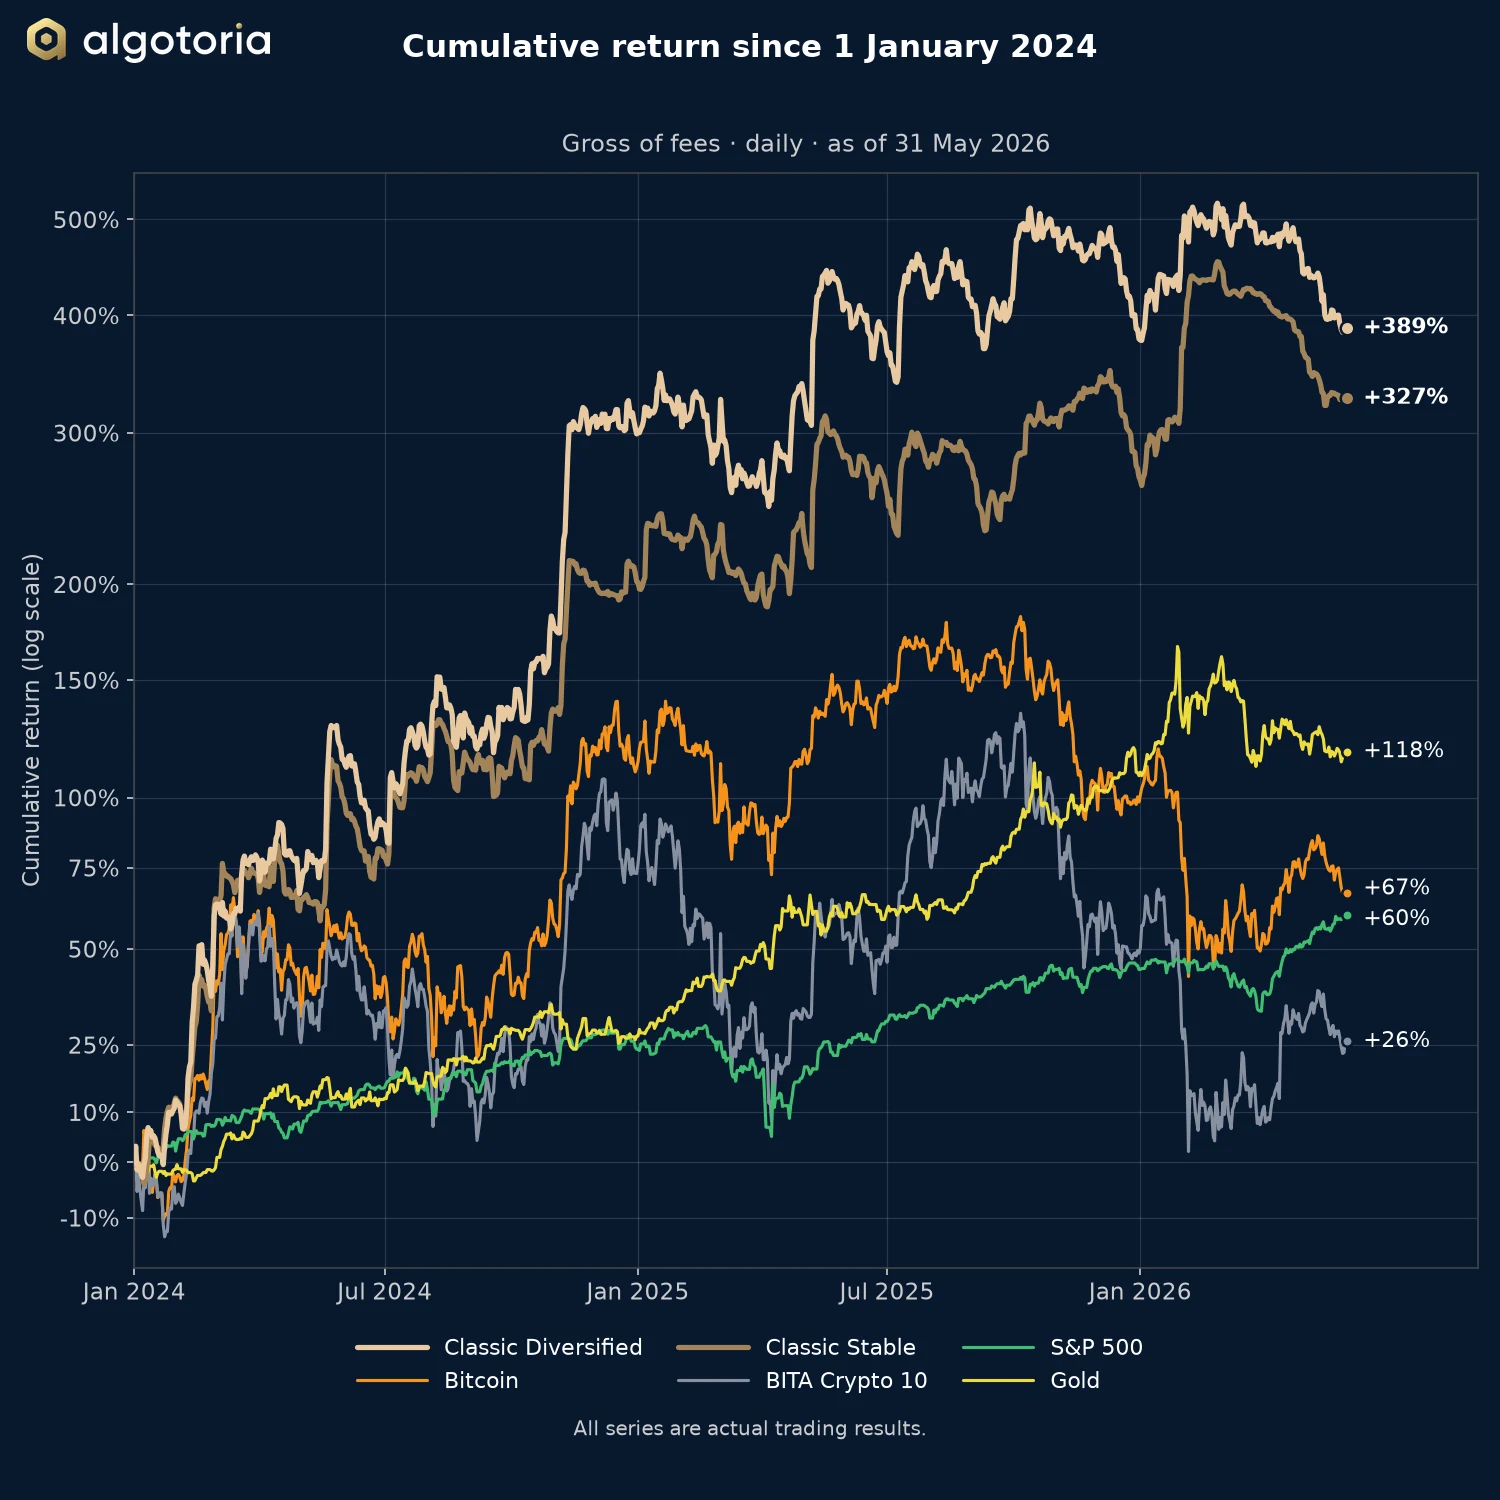
Monthly report: May 2026

Classic Diversified returned −9.69% in May 2026 and Classic Stable −8.11%, in a fourth month of low volatility that suited trend-following algorithms least.

Read →
Performance reports

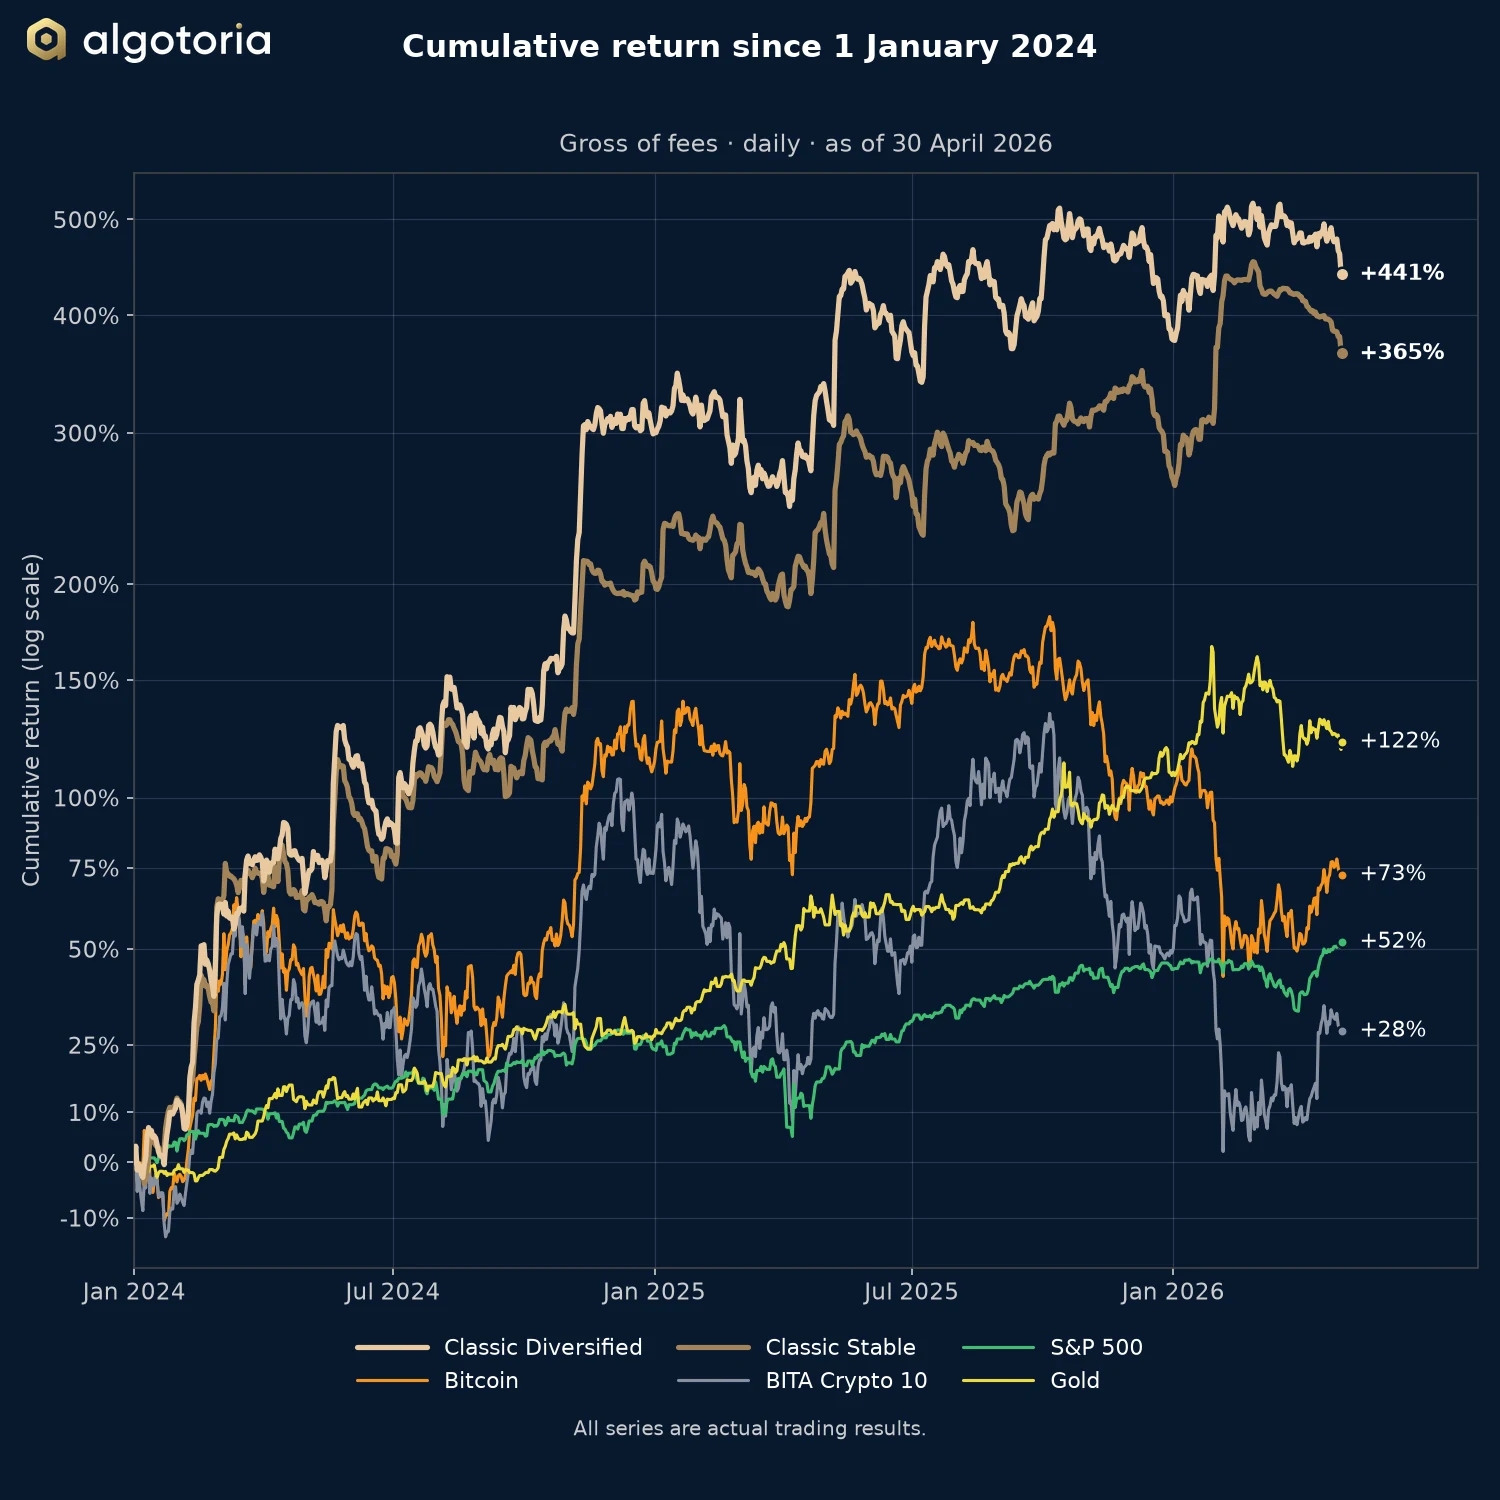
Monthly report: April 2026

Classic Diversified returned −7.52% in April 2026 and Classic Stable −10.26%, as low volatility in the crypto market limited the trend-following algorithms.

Read →
Strategy and risk

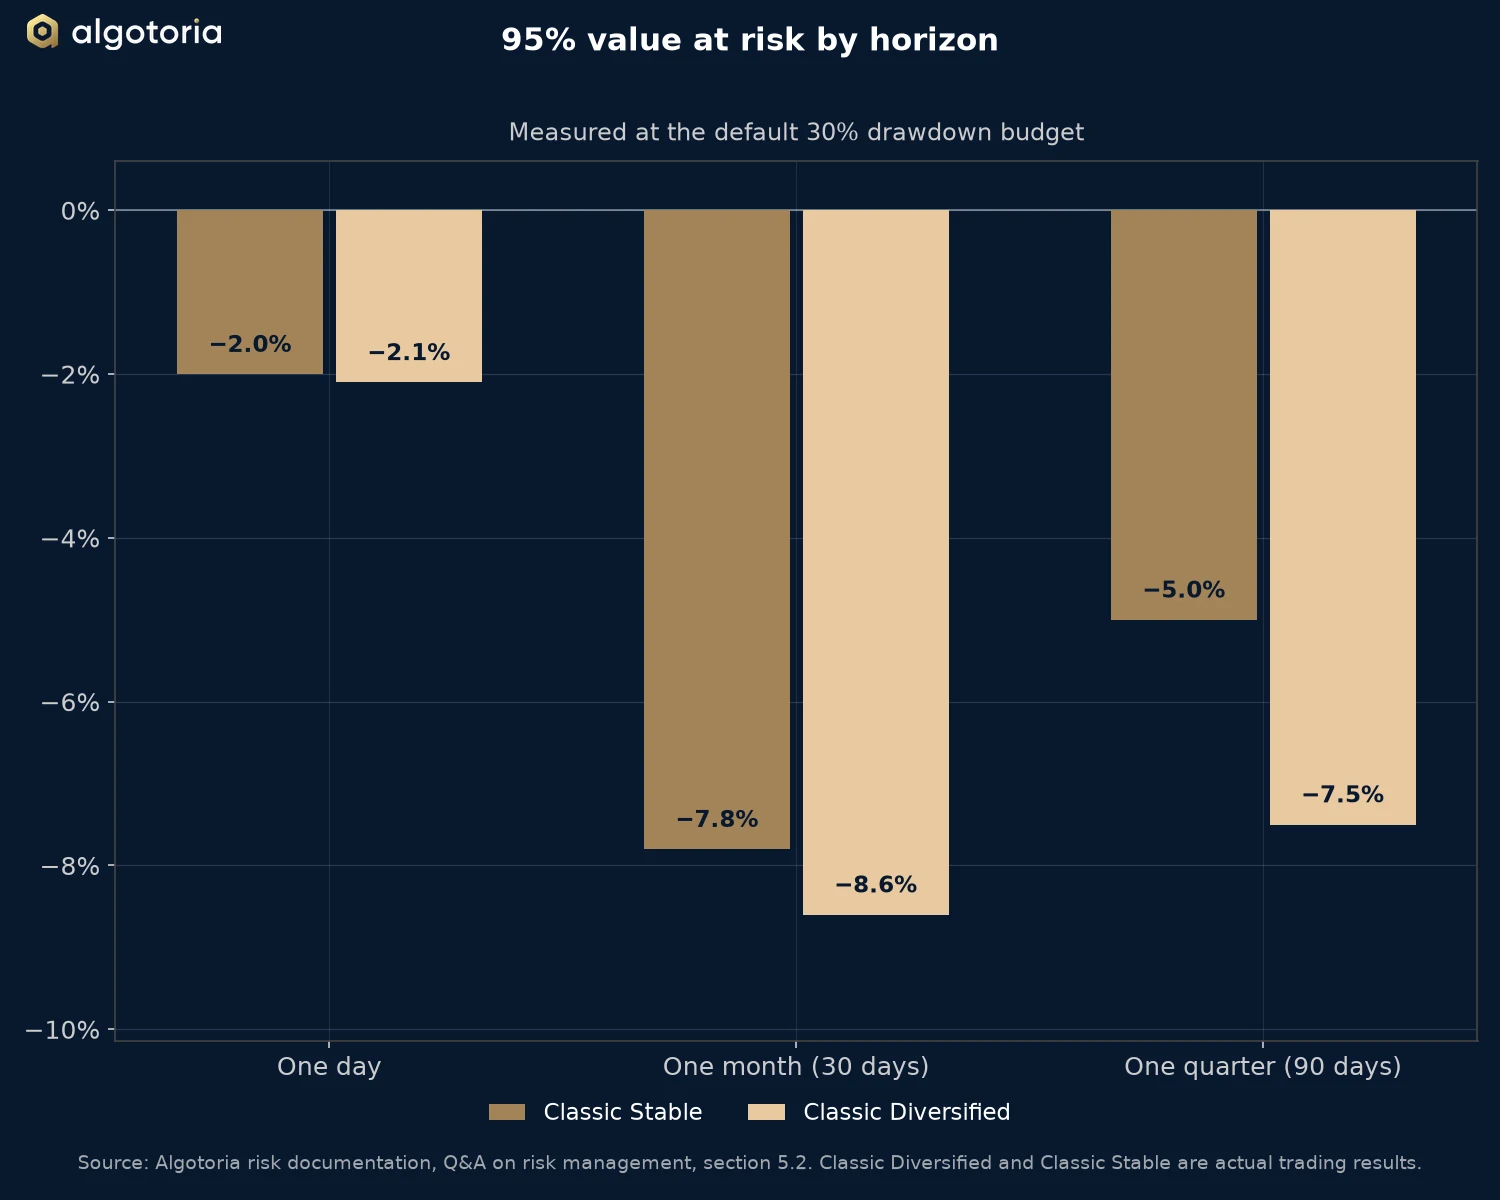
Value at risk by strategy: how to read the numbers

What 95% value at risk says about Classic Diversified and Classic Stable over one day, one month and one quarter, and what the measure leaves out.

Read →
Performance reports

Monthly report: March 2026

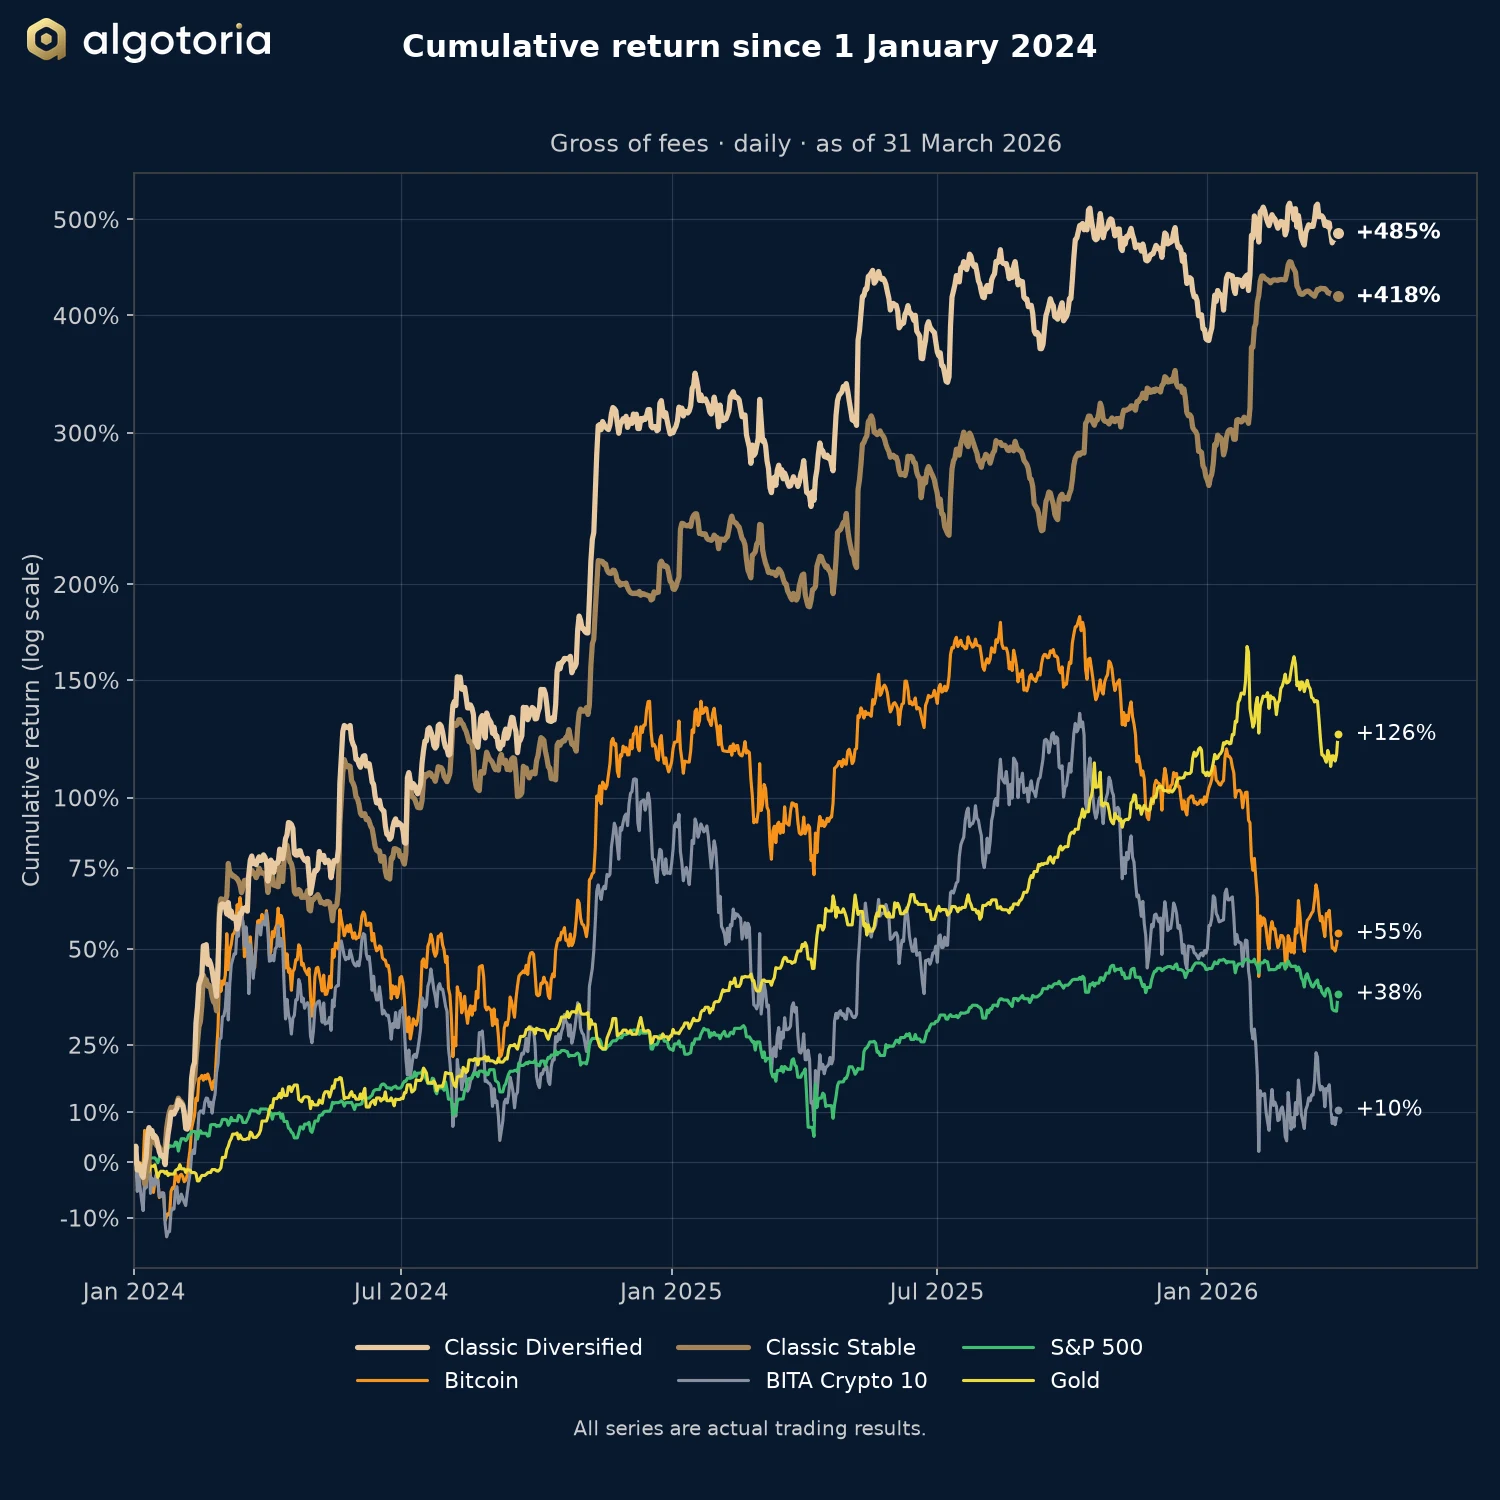
In a sideways March 2026 Classic Diversified returned −4.45% and Classic Stable −5.53%. For the first quarter they stood at +22.29% and +40.88%.

Read →
Performance reports

Monthly report: February 2026

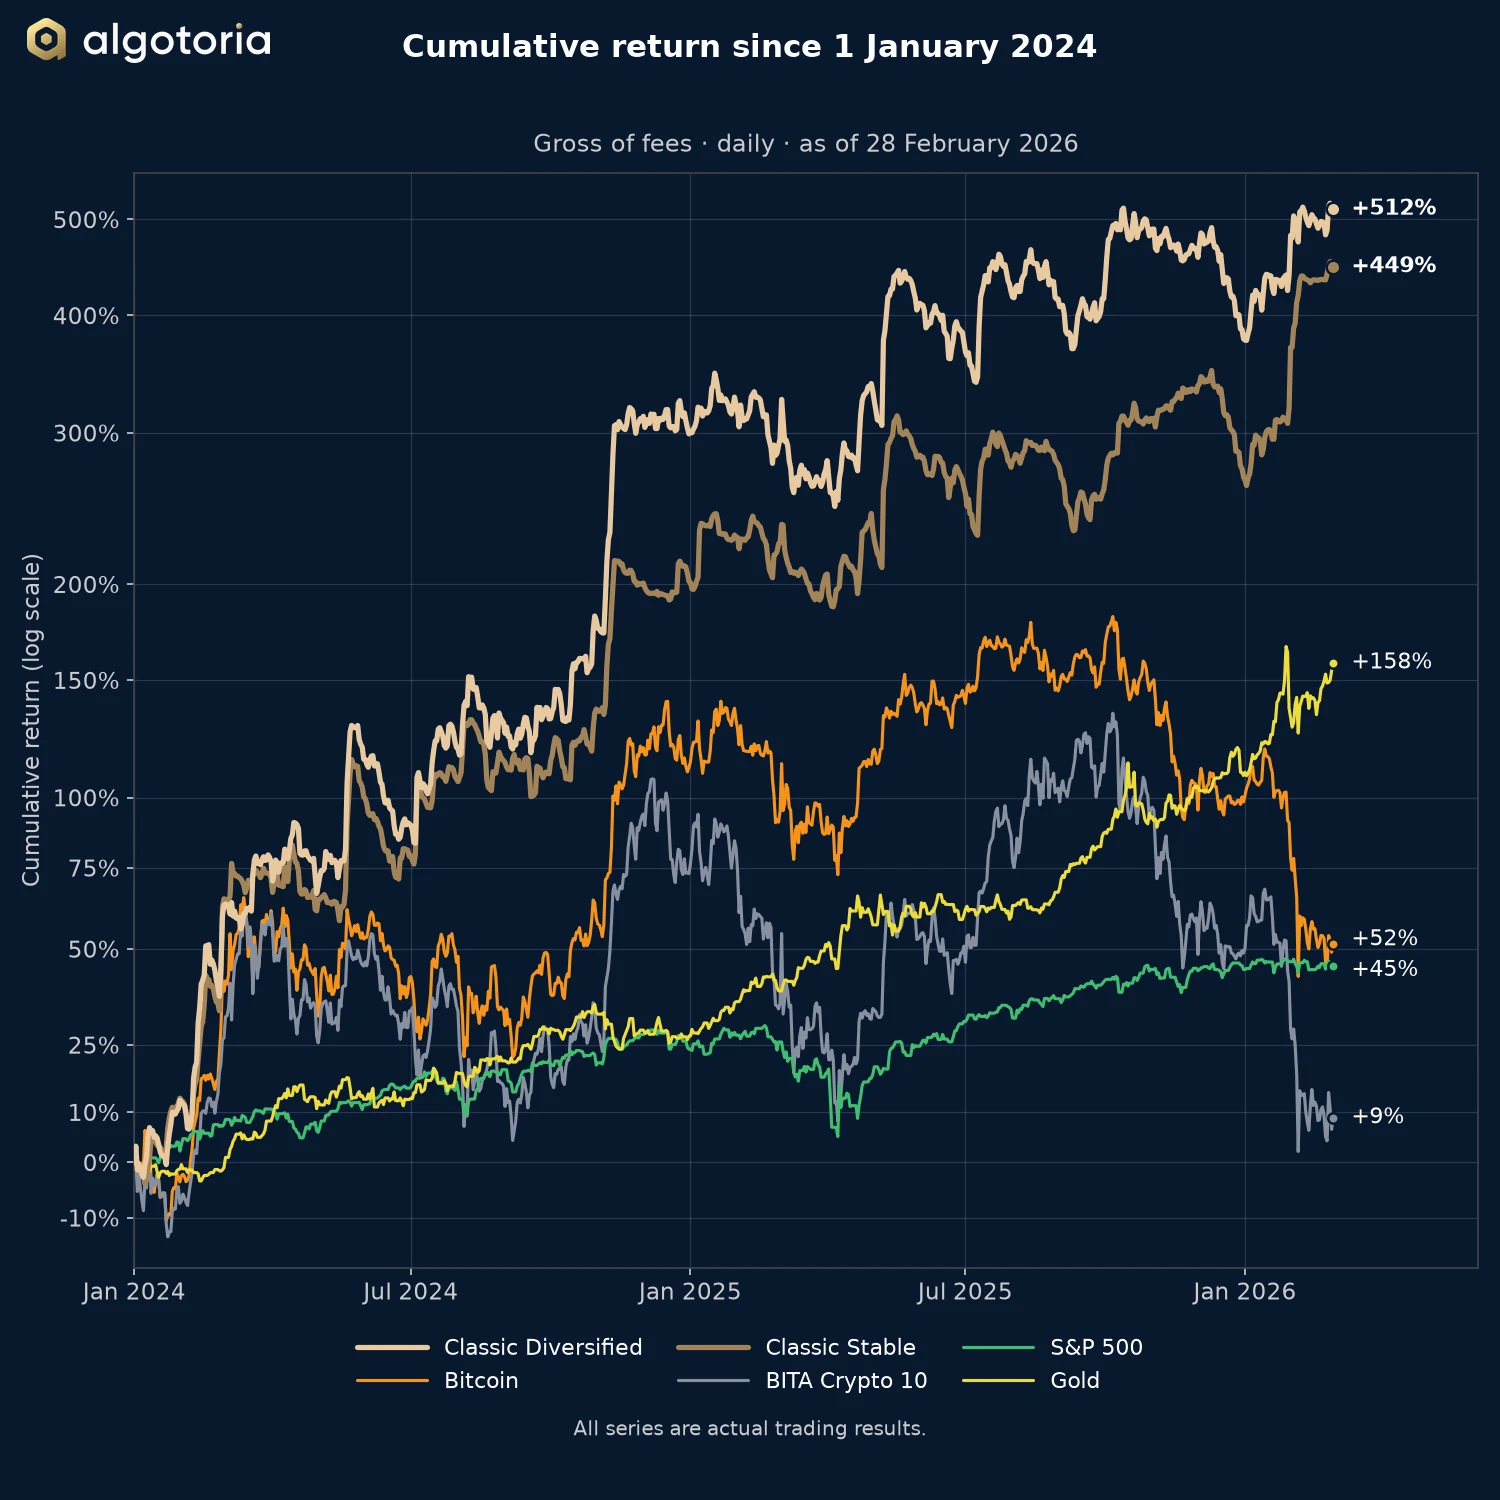
Classic Diversified returned +5.13% in February 2026 and Classic Stable +16.58%, while Bitcoin returned −14.95% in a third month of ETF outflows.

Read →
Strategy and risk

Why investors can lose money in a profitable strategy

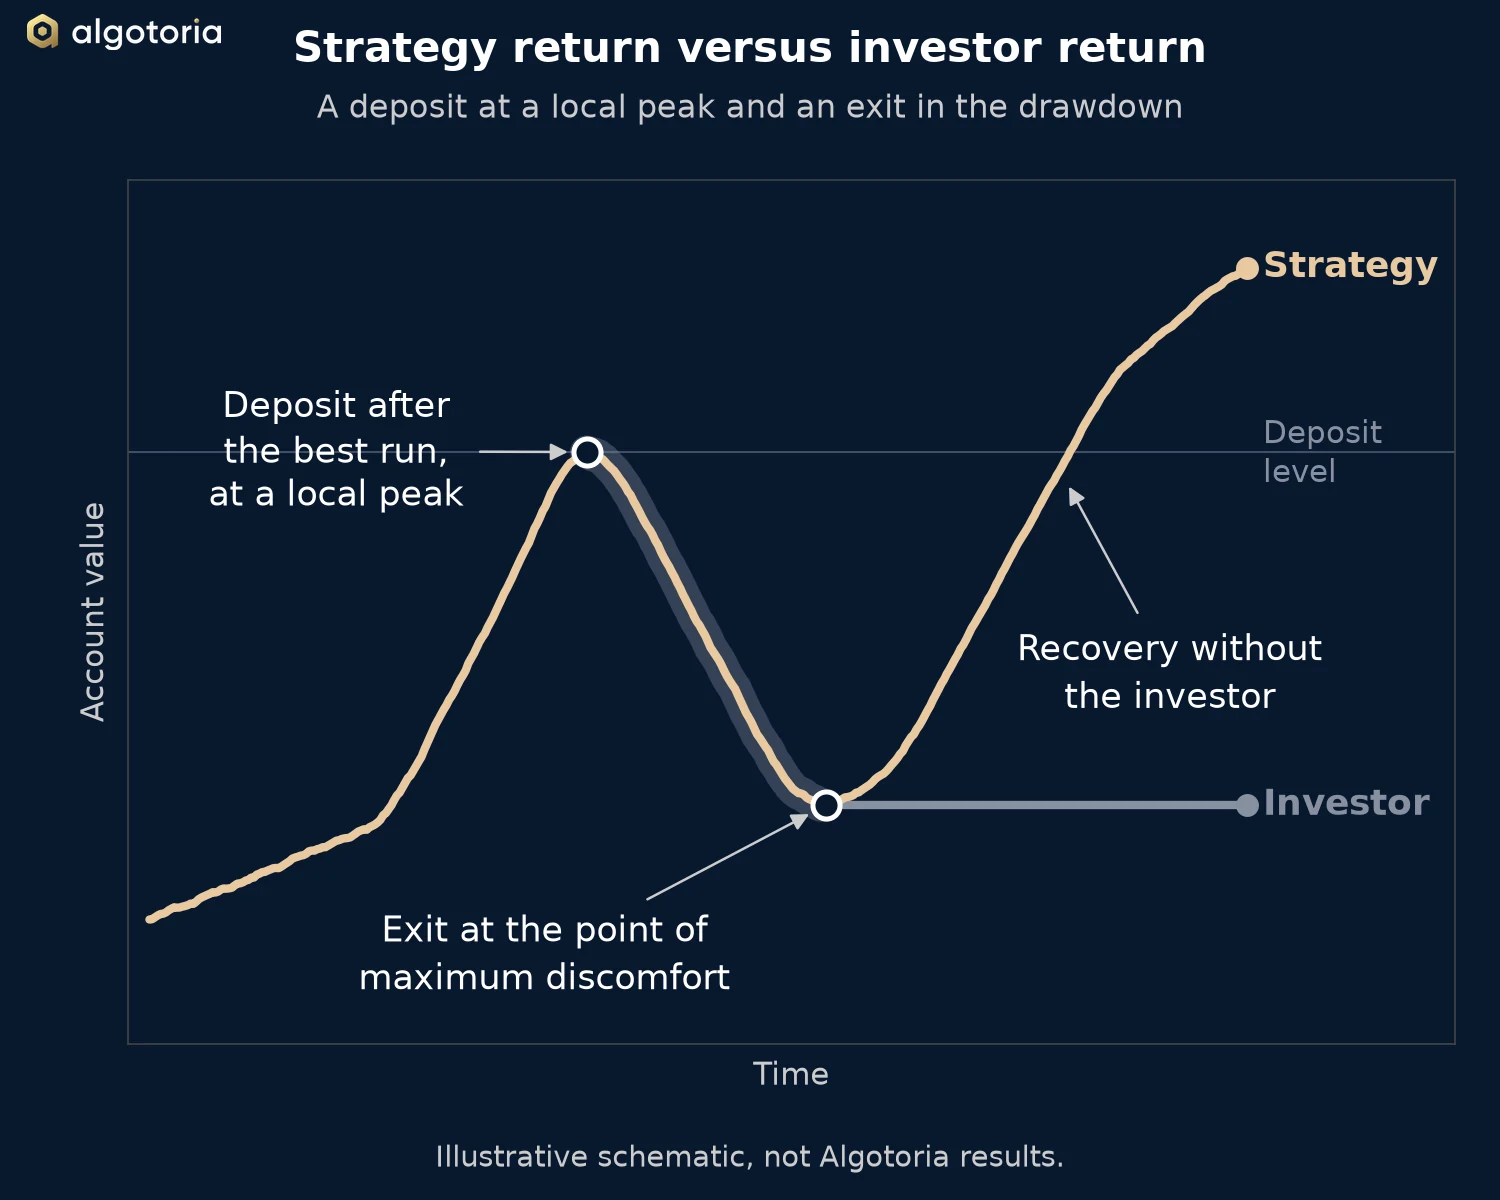
A strategy can have positive expectancy and controlled drawdowns, yet an investor can still lose money. The cause is usually timing and behaviour, not the model.

Read →
Market commentary

The February 2026 crypto sell-off and why trend-following gained

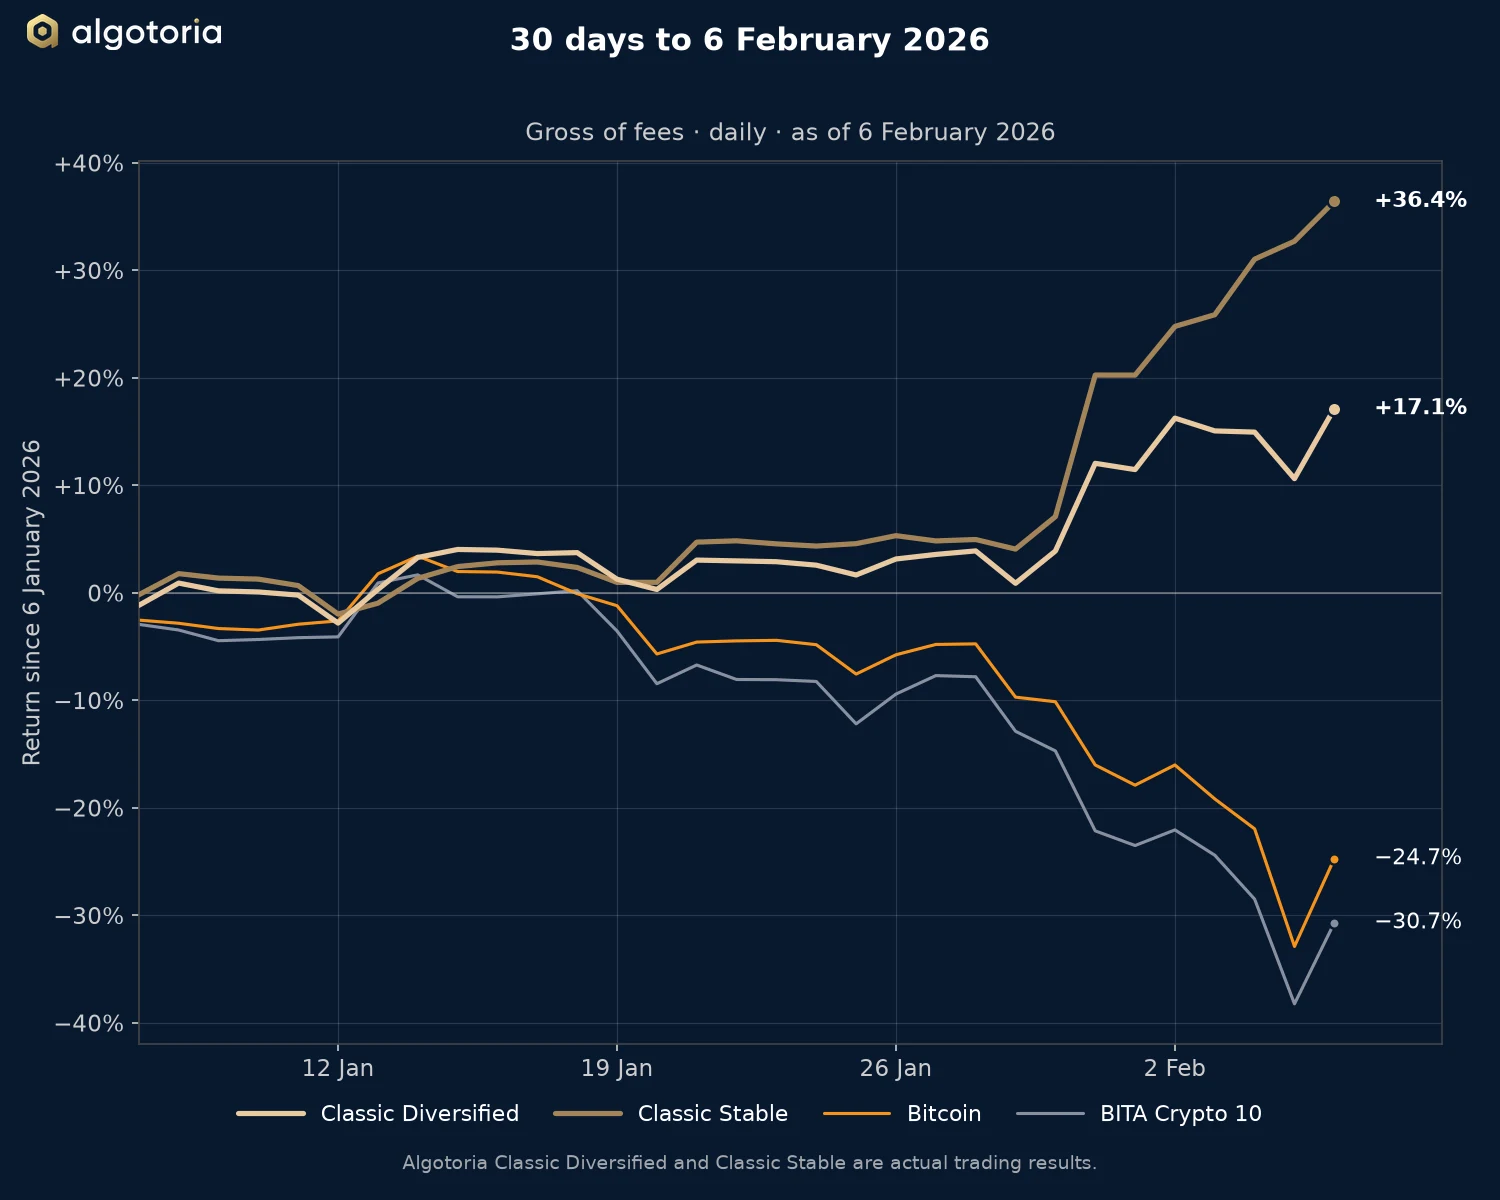
In the month to 6 February 2026 Classic Stable returned +36.42% and Classic Diversified +17.15%, while Bitcoin returned −24.73%.

Read →
Performance reports

Monthly report: January 2026

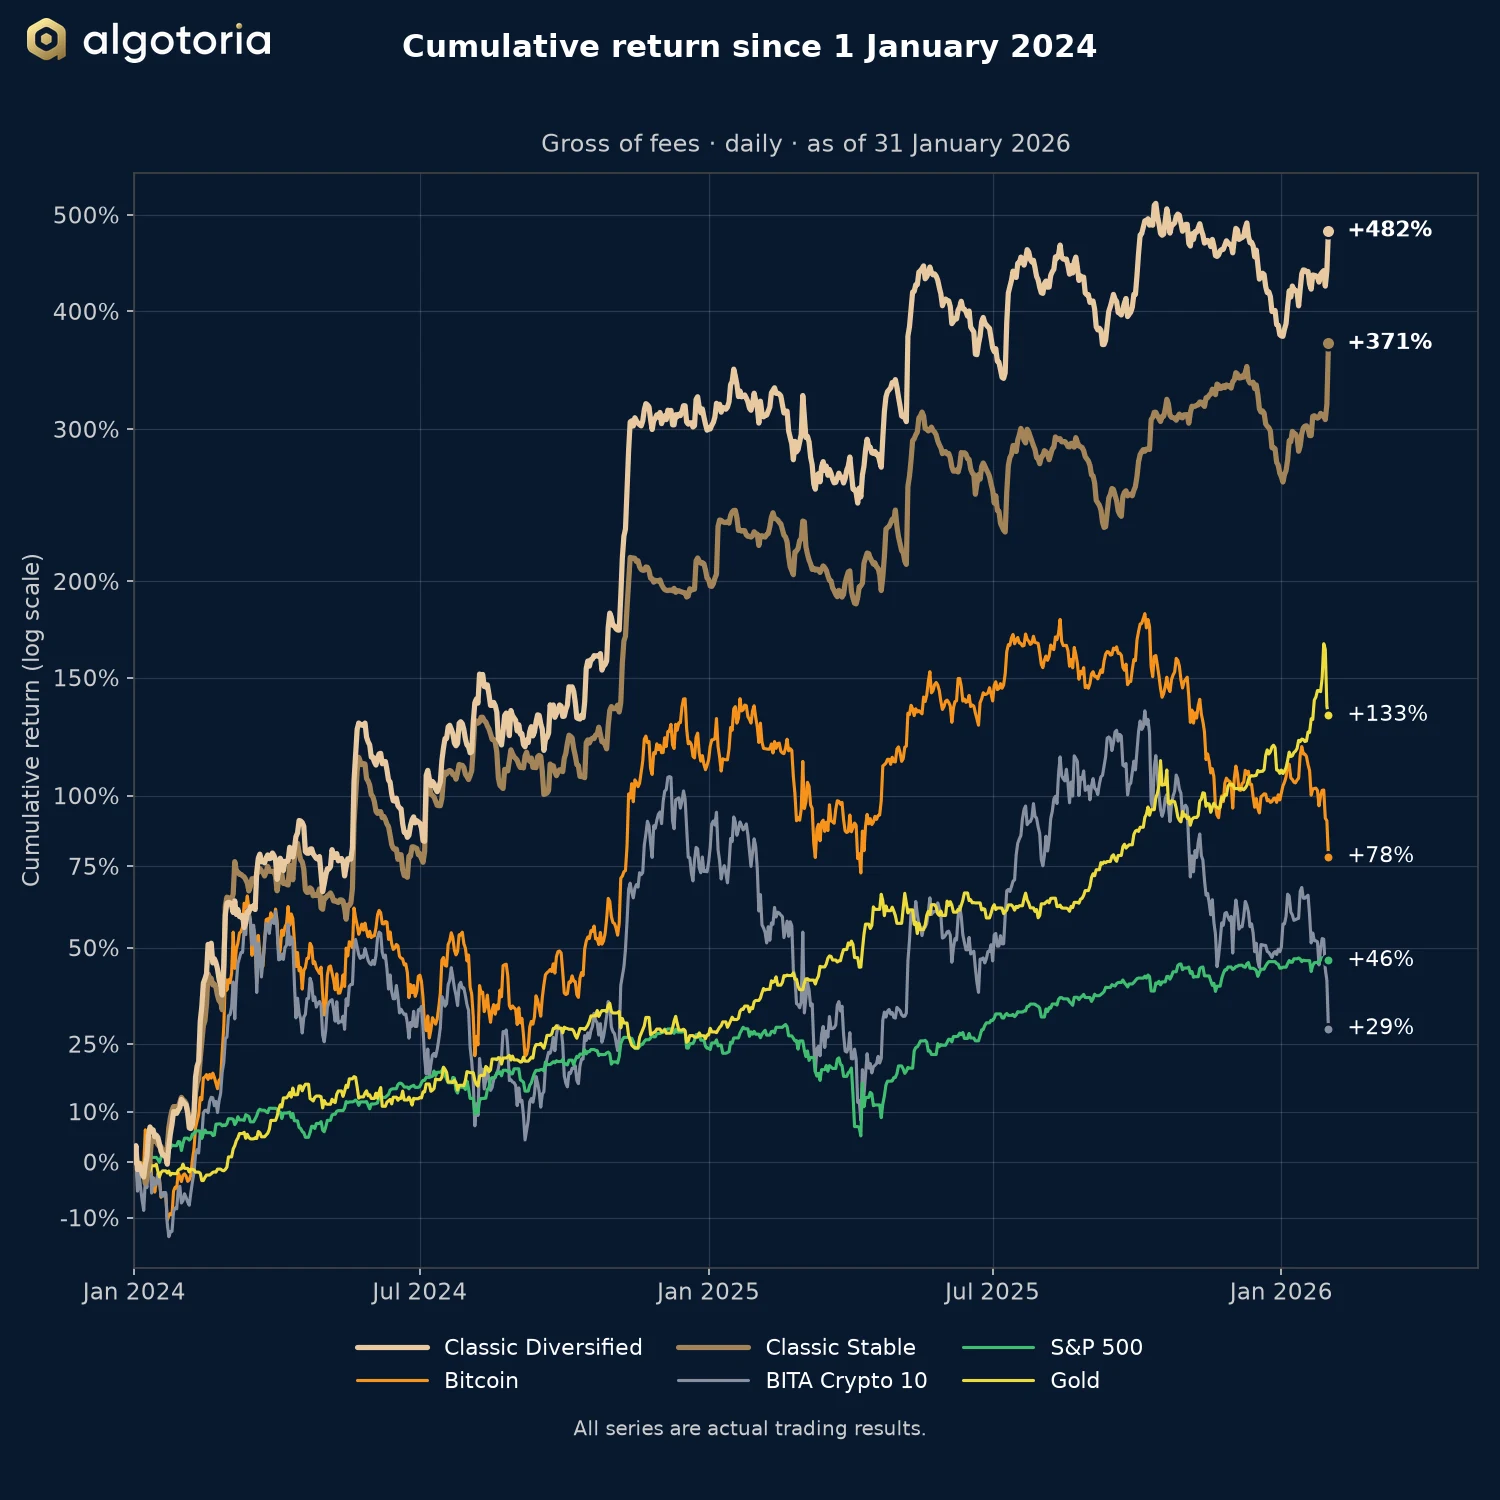
Classic Diversified returned +21.73% in January 2026 and Classic Stable +27.91%, in a month when Bitcoin returned −10.15%.

Read →
Strategy and risk

New trade filters for Bitcoin, Ethereum and Solana

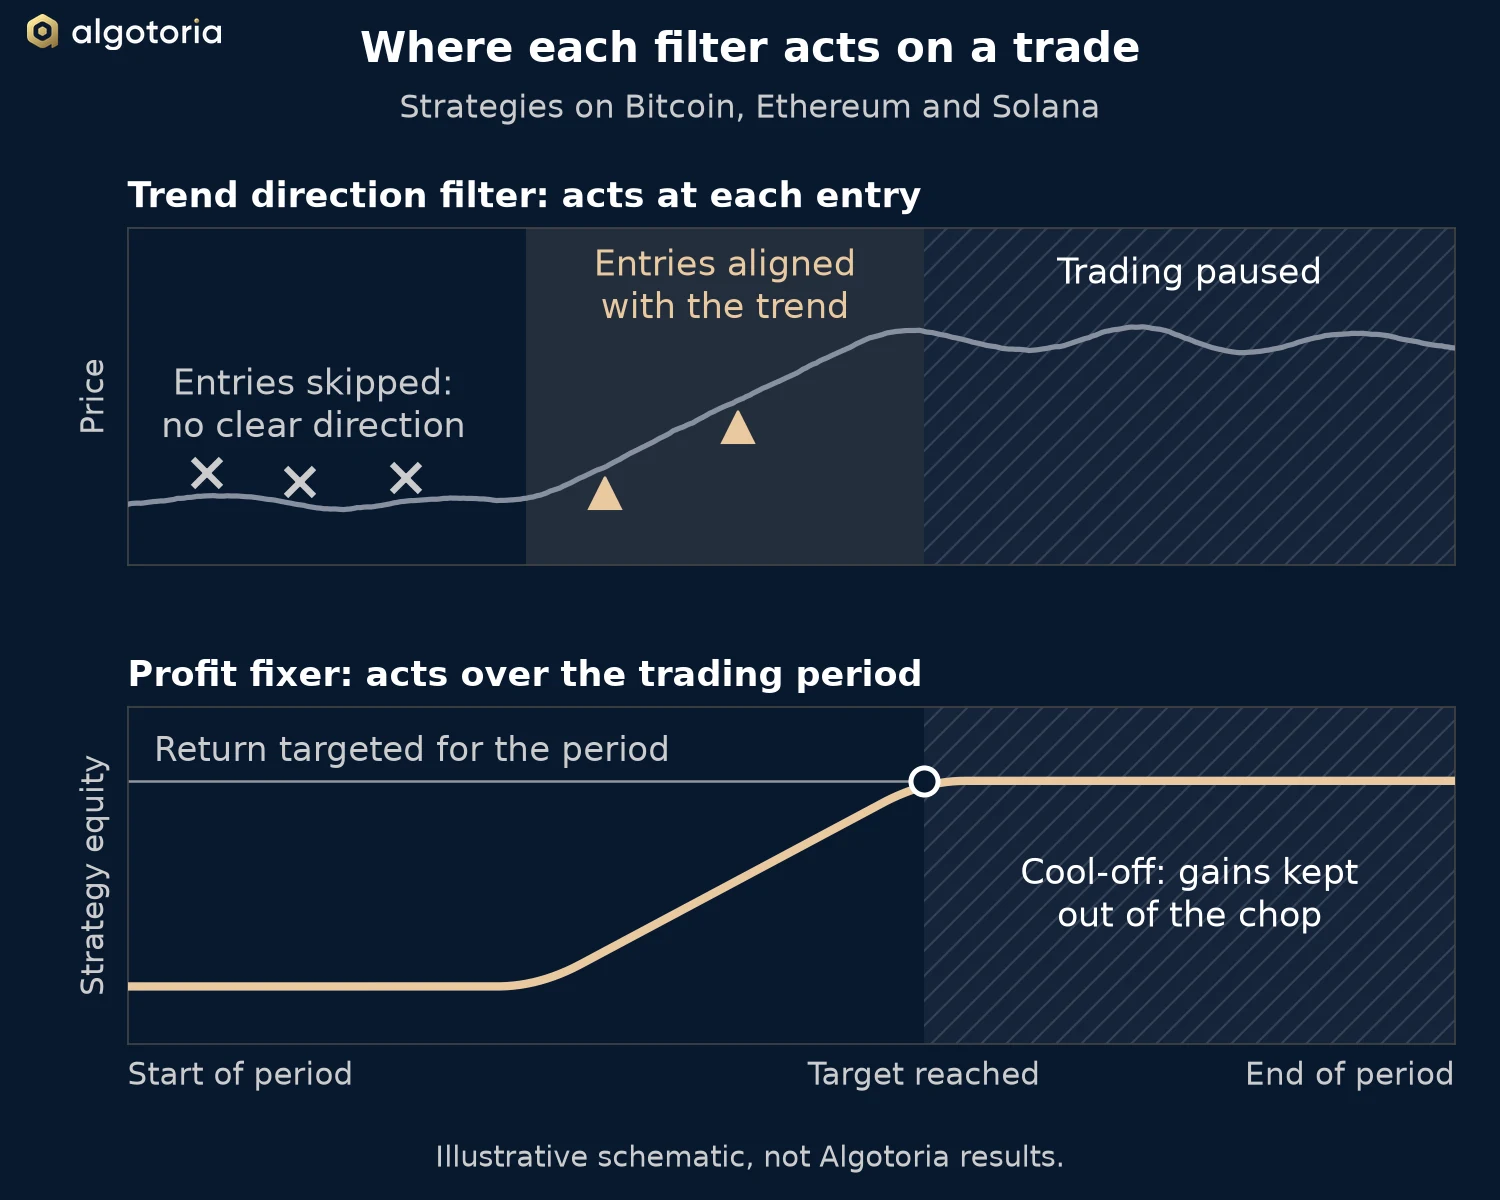
Two updates to the strategies on the largest assets: a trend direction filter that removes low-quality entries in flat markets, and a profit fixer that protects gains within a period.

Read →
Performance reports

Monthly report: December 2025 and full year

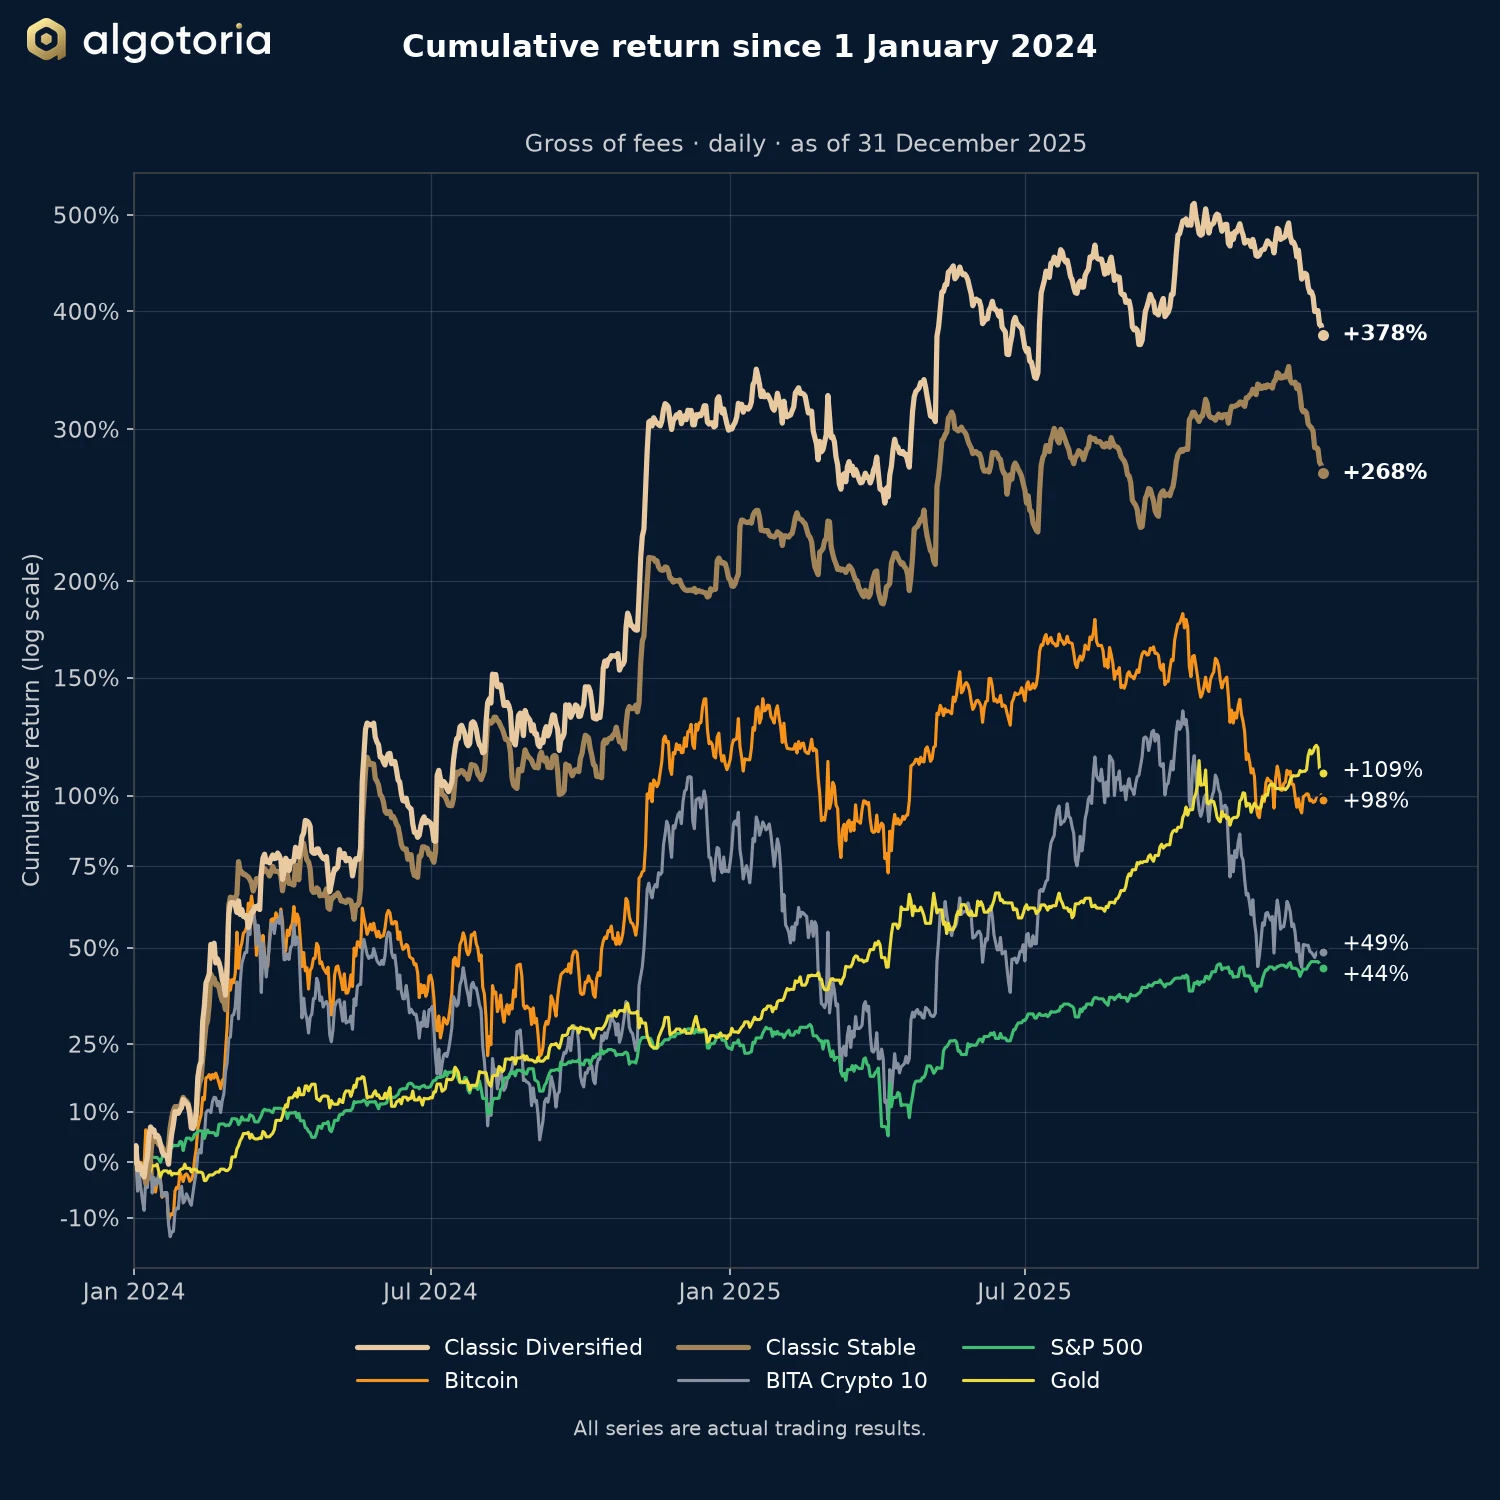
In December 2025 Classic Diversified returned −15.64% and Classic Stable −14.88%. For the year they returned +19.82% and +21.96%, against −6.35% for Bitcoin.

Read →

2025

Performance reports

Monthly report: November 2025

Classic Stable returned +5.17% in November 2025 and Classic Diversified −3.54%, in a month when Bitcoin returned −17.55%.

Read →
Performance reports

Monthly report: October 2025

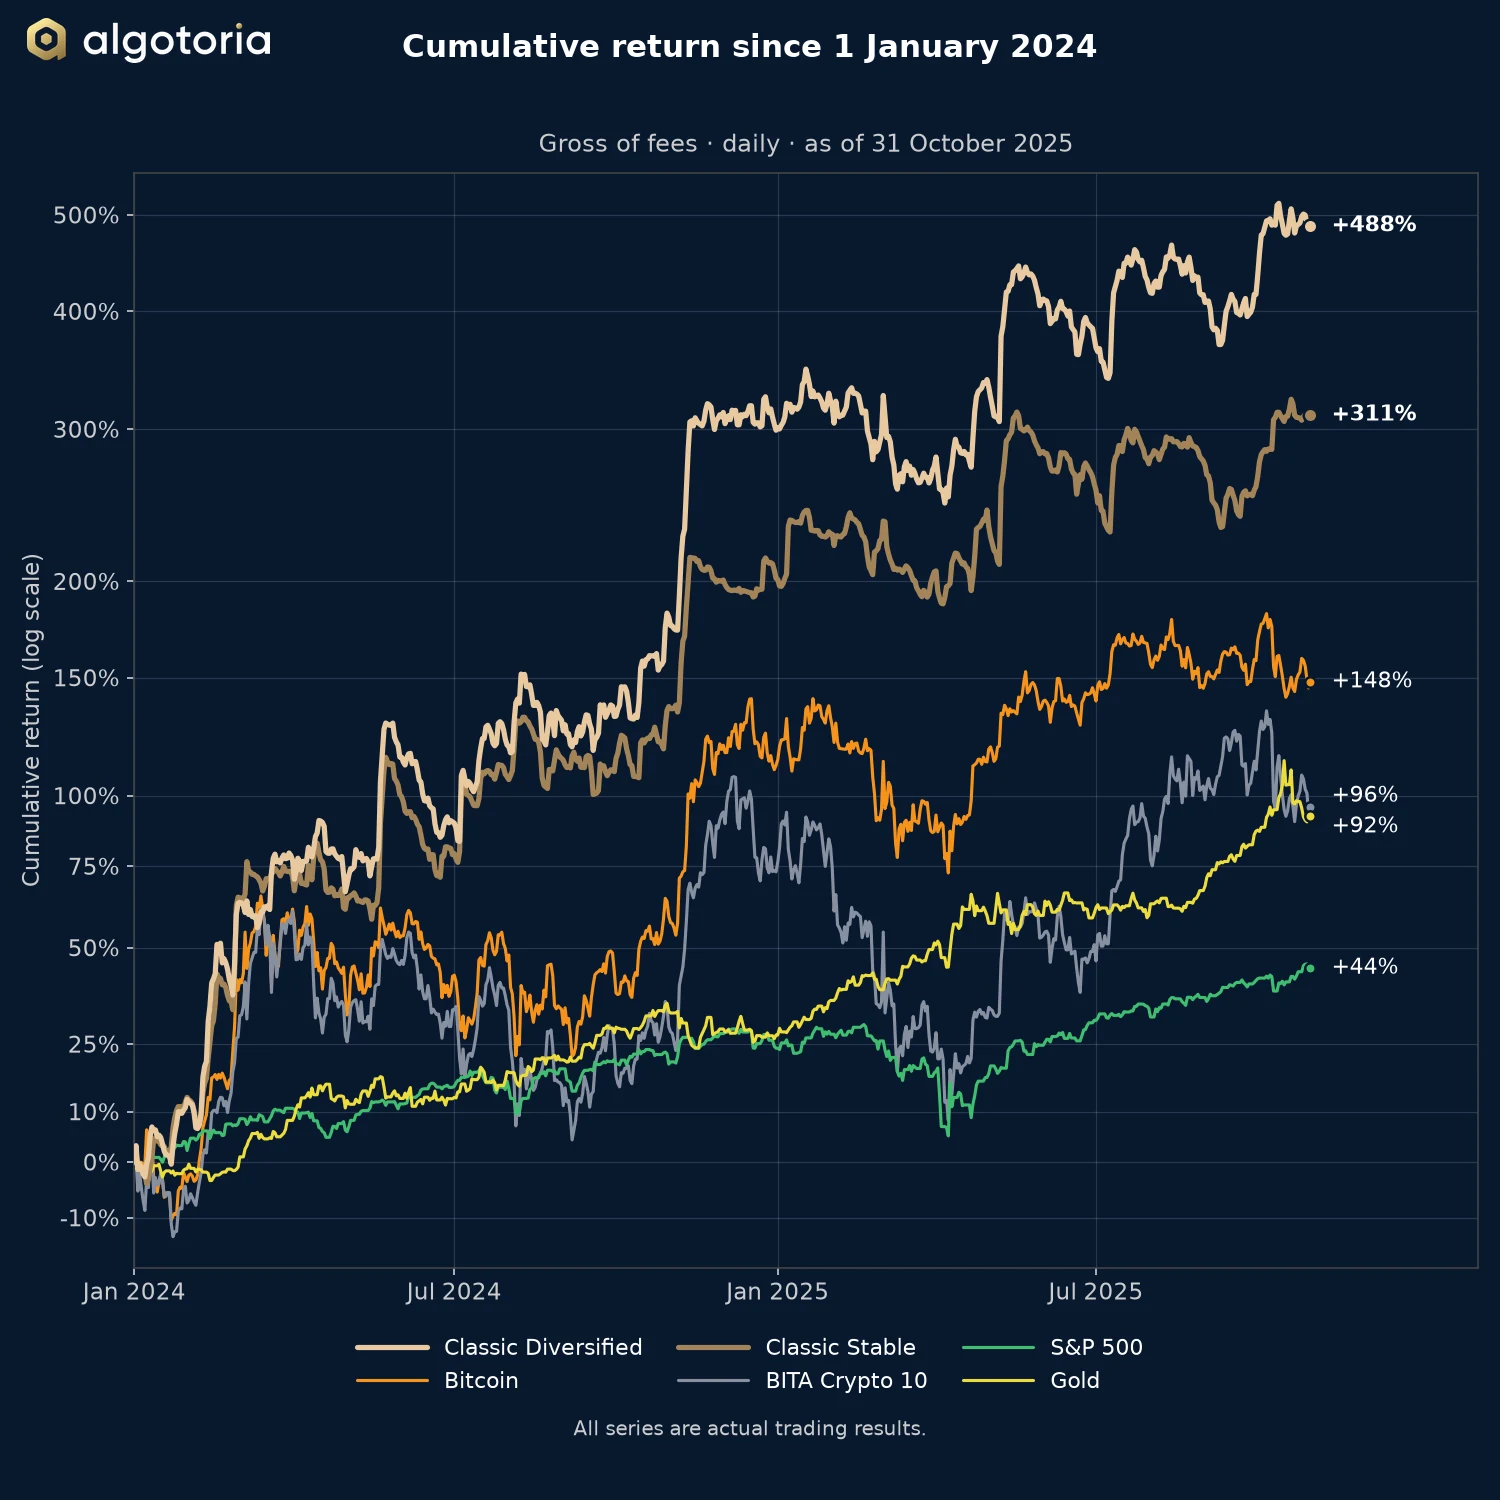
Classic Stable returned +14.53% in October 2025 and Classic Diversified +13.90%, in a month with a record Bitcoin high and a sharp sell-off.

Read →
Market commentary

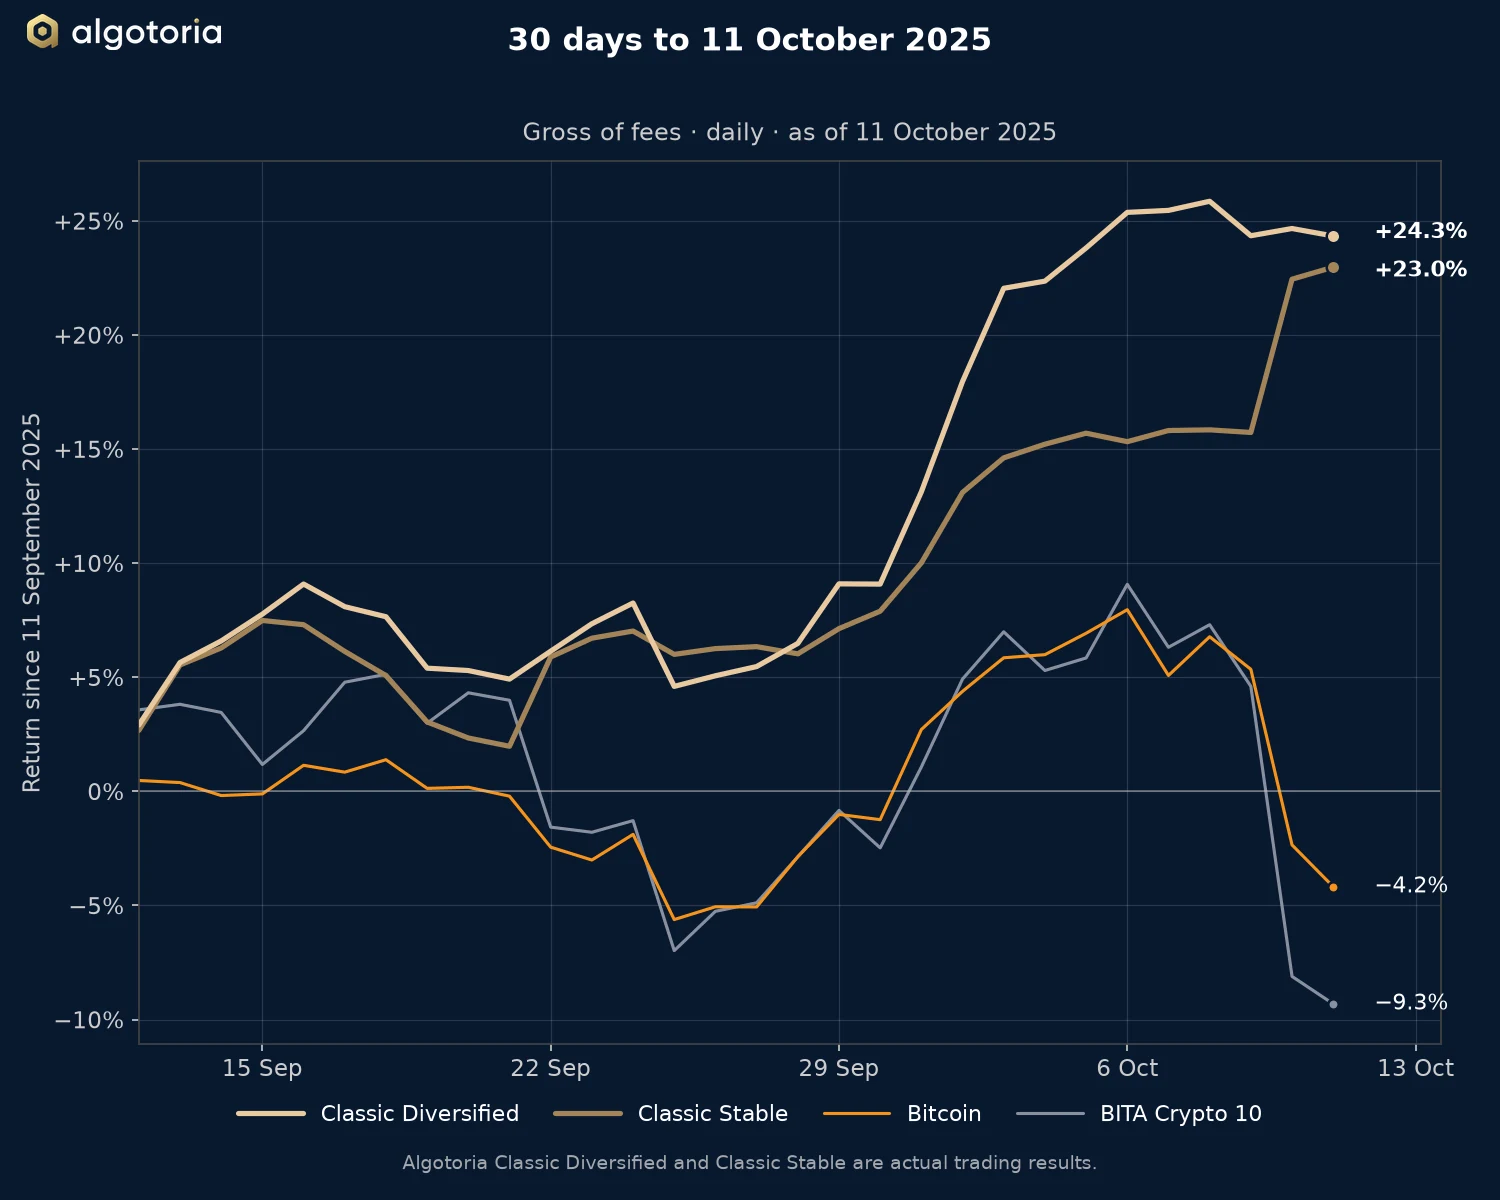
The 10 October 2025 crash and the trend-following response

On 10 October 2025 Classic Stable returned +5.80% while Bitcoin returned −7.30%. Over 30 days Classic Stable returned +22.97%.

Read →
Performance reports

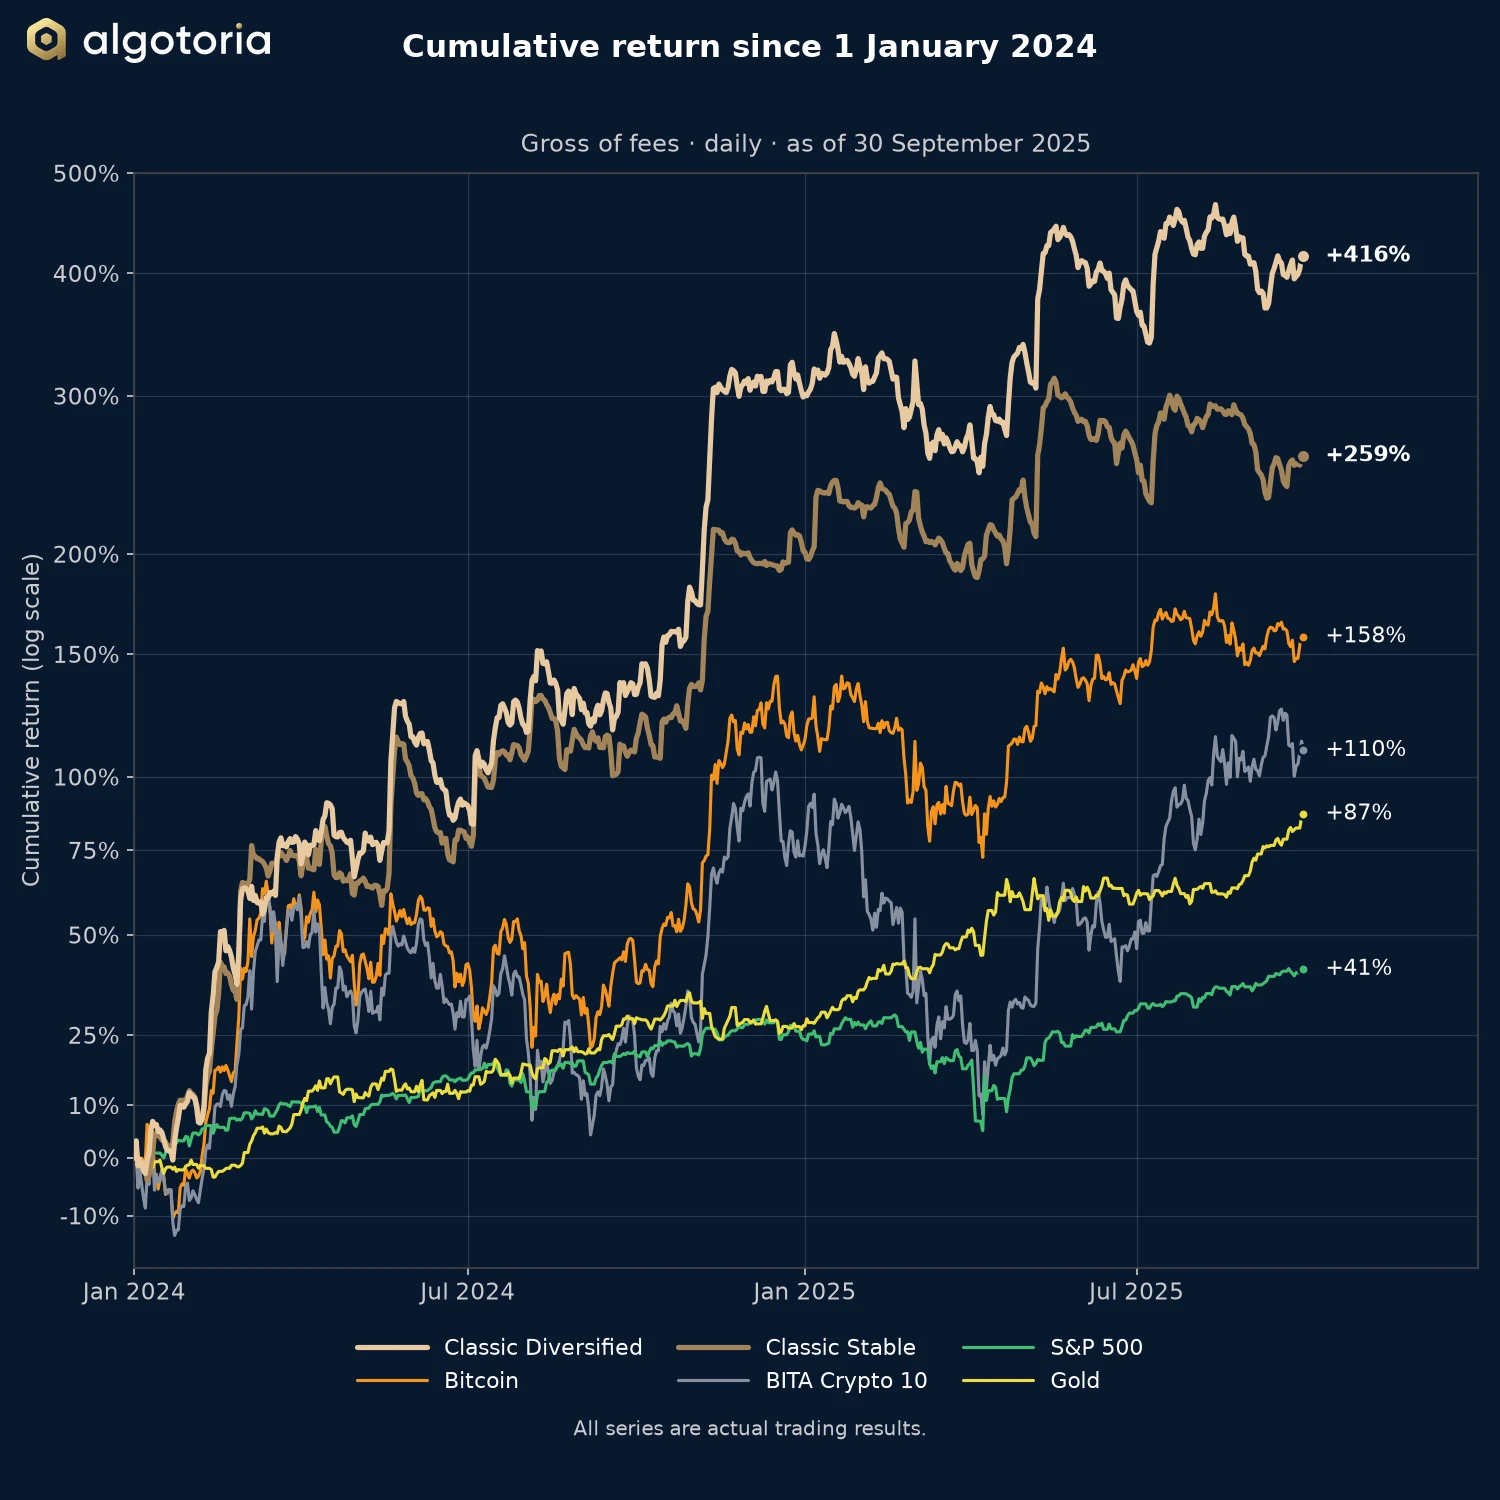
Monthly report: September 2025

Classic Diversified returned +0.05% in September 2025 and Classic Stable −4.72%, in a month of low volatility that ended with a breakout in the first days of October.

Read →
Performance reports

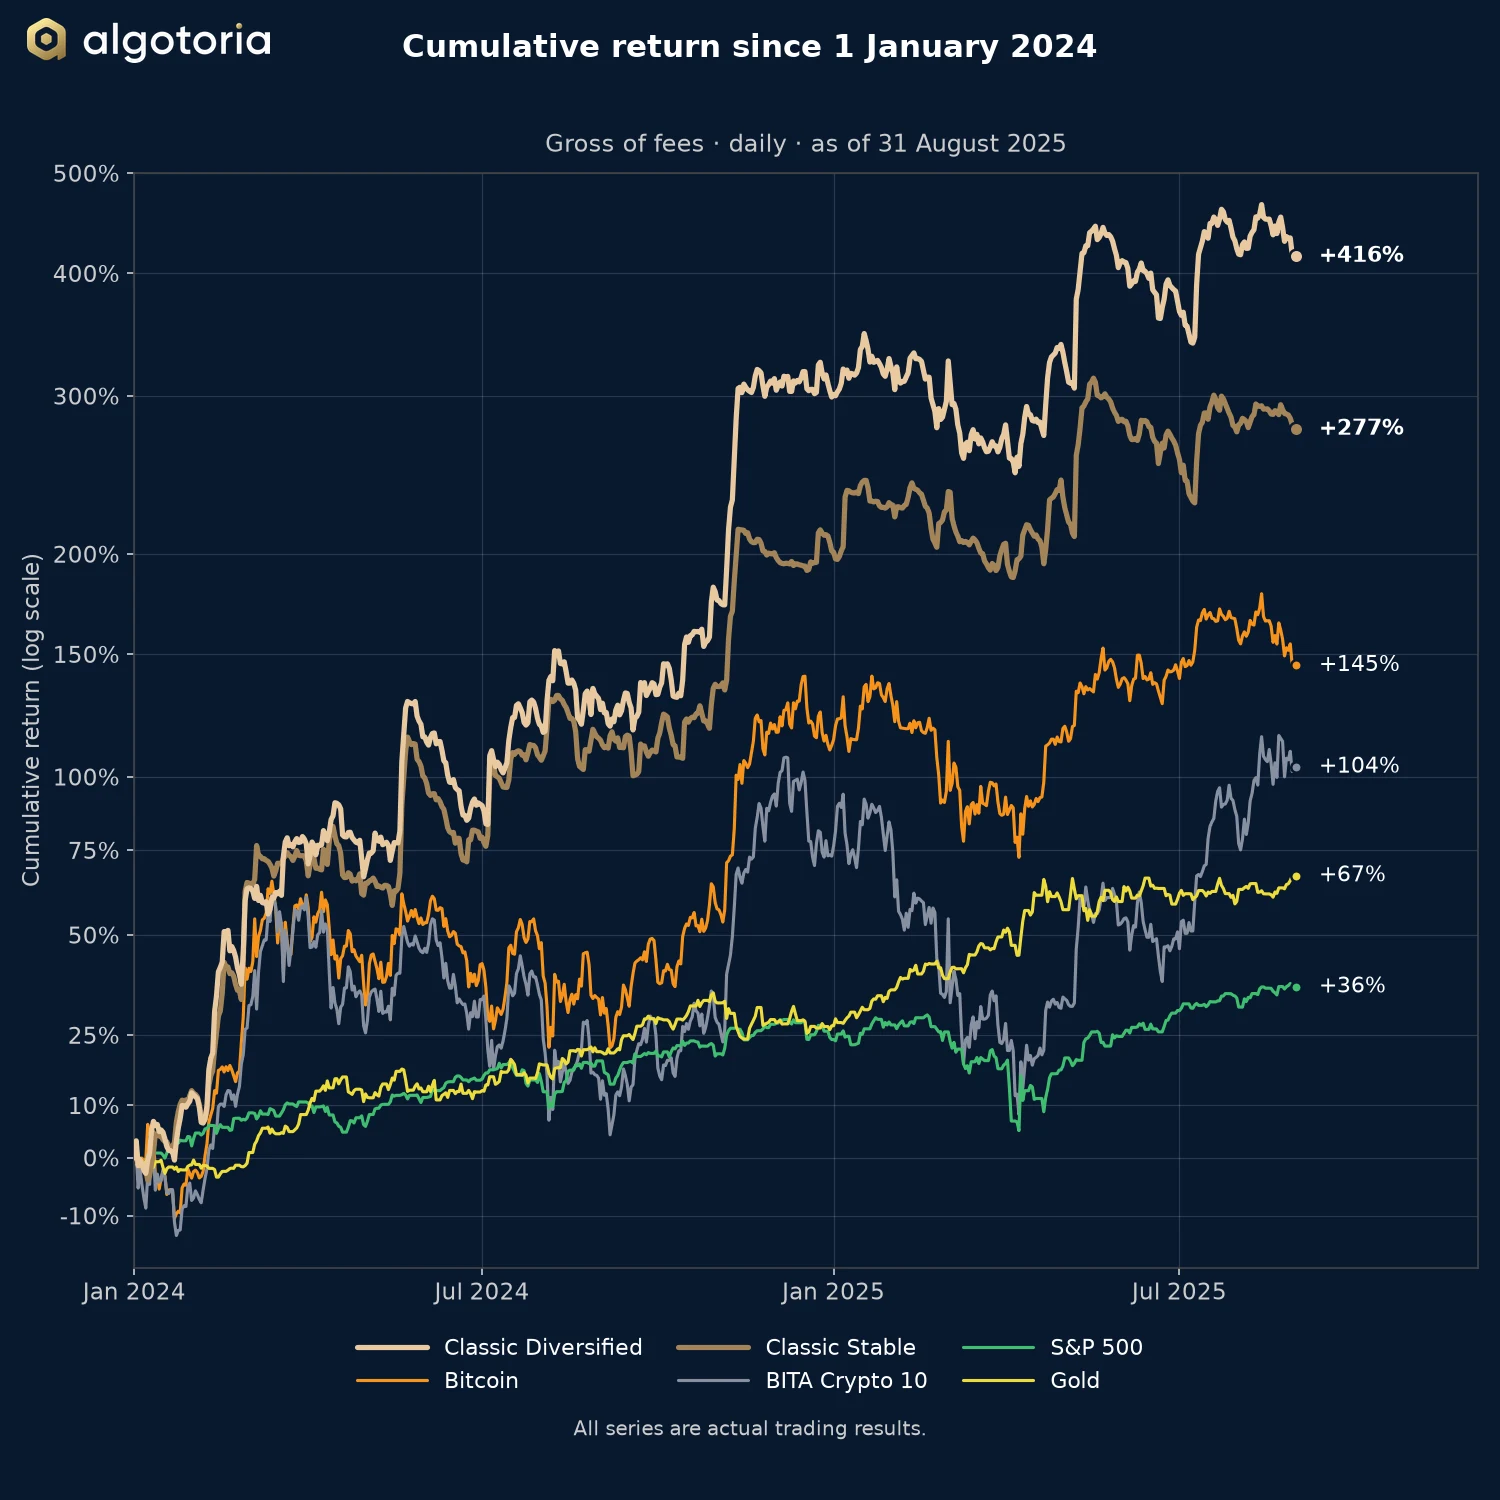
Monthly report: August 2025

Classic Stable returned +0.52% in August 2025 and Classic Diversified −1.35%, in a month of low volatility in which Bitcoin returned −6.49%.

Read →
Market commentary

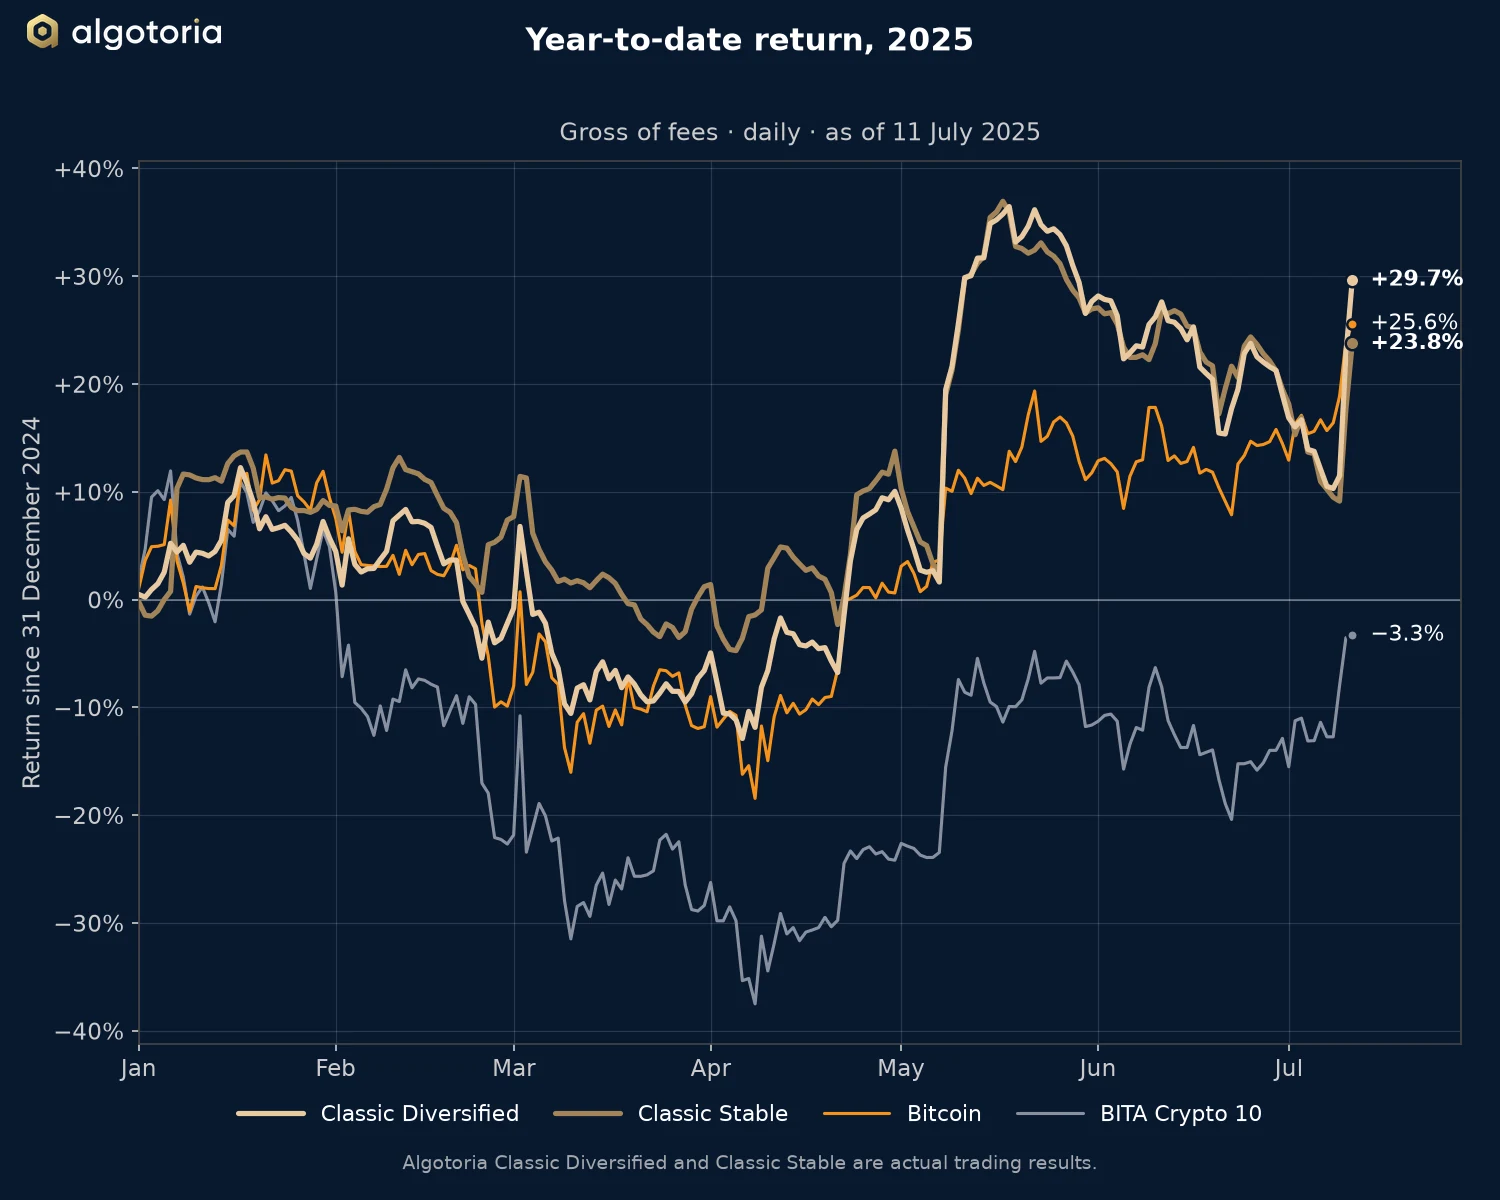
July 2025 rally: year-to-date returns against the market

By 11 July 2025 Classic Diversified was up +29.7% for the year, ahead of Bitcoin at +25.6%, while the BITA Crypto 10 index stood at −3.3%.

Read →
Market commentary

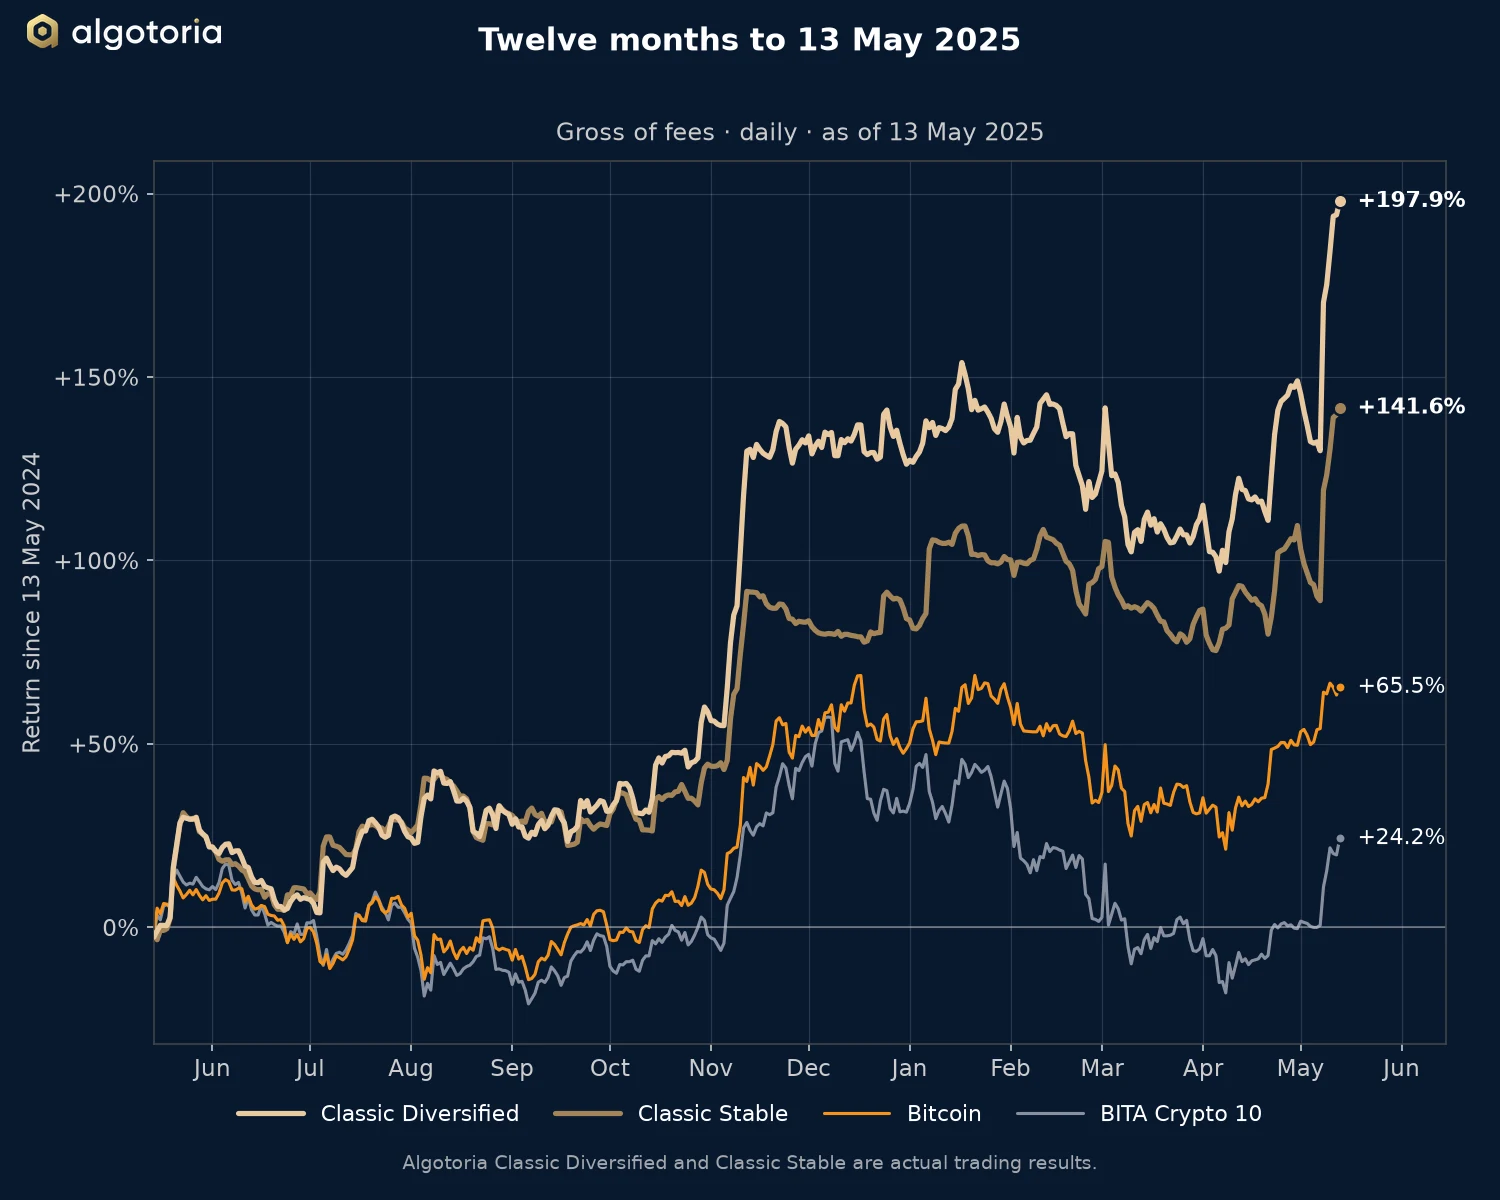
Twelve months to May 2025: the strategies against Bitcoin

In the twelve months to 13 May 2025 Classic Diversified returned +197.90% and Classic Stable +141.59%, against +65.45% for Bitcoin.

Read →
Performance reports

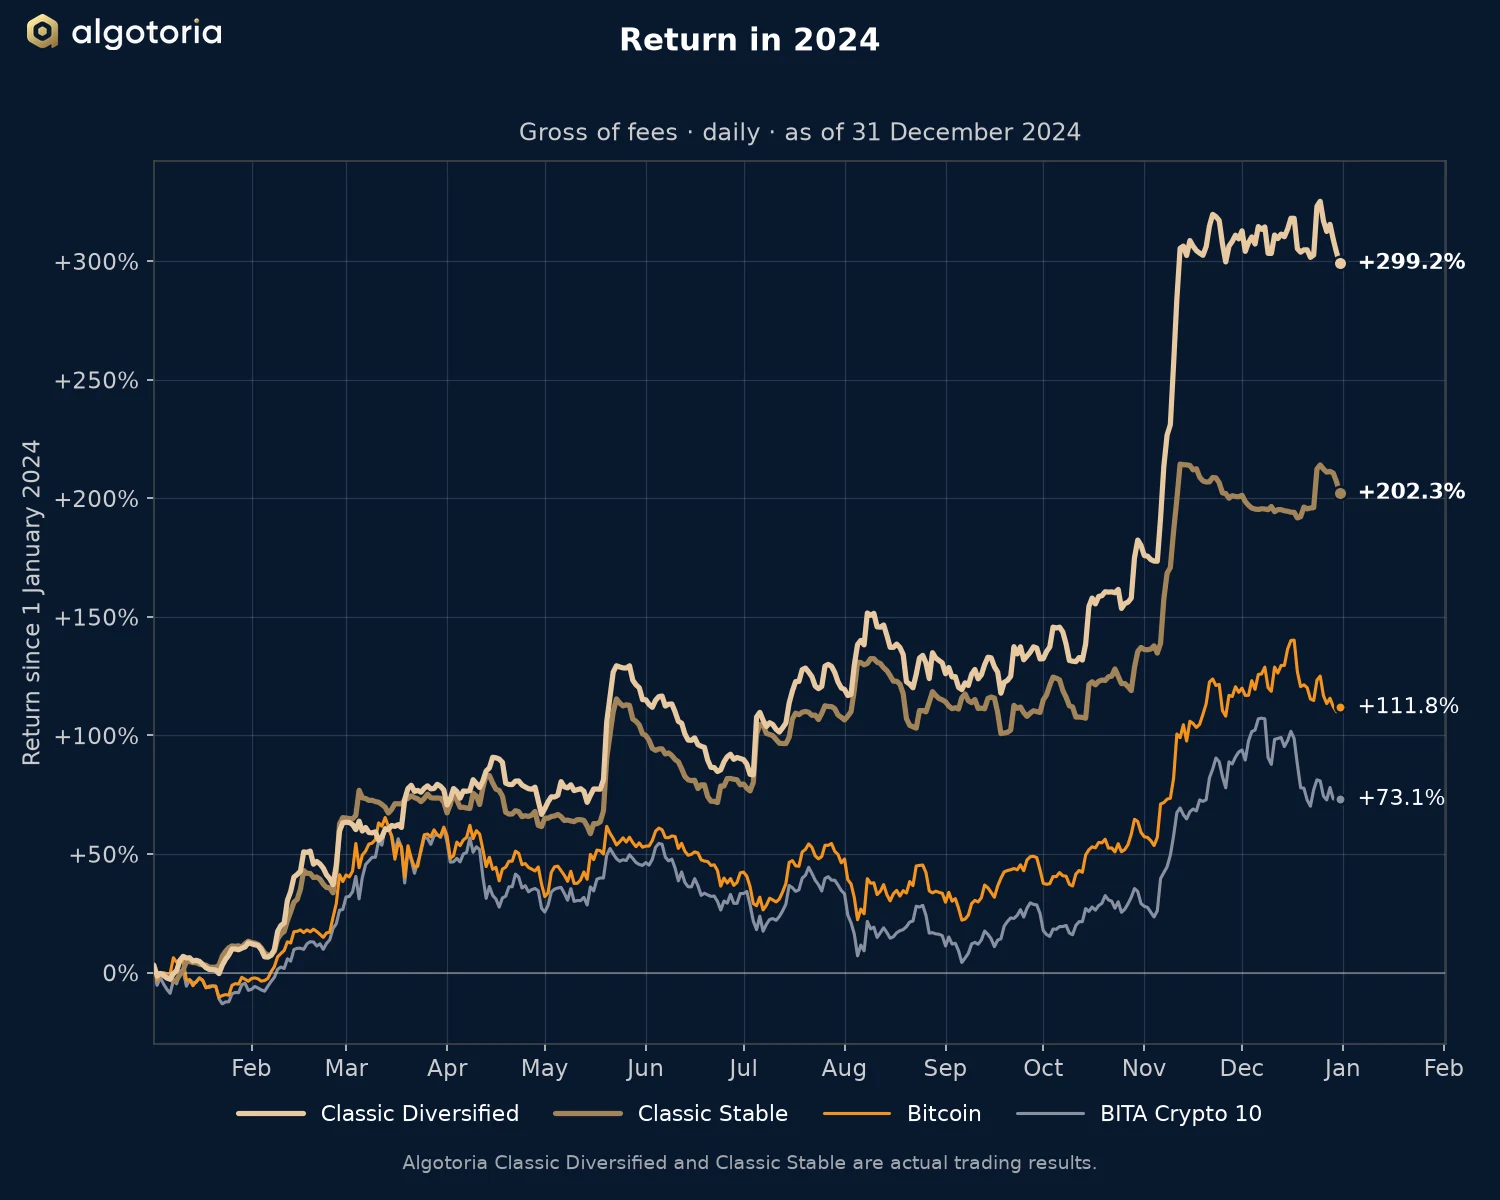
Results for 2024: Classic Diversified and Classic Stable

In 2024 Classic Diversified returned +304.42% and Classic Stable +201.67%, before performance fees. Bitcoin returned +112% over the year.

Read →

Get Started

Typical onboarding takes one business day, plus the international bank transfer if you fund from fiat.

Start a conversation

Tell us a little about yourself and a co-founder will reply within one business day.

By submitting, you agree we may contact you at the details above. We do not share your data with third parties. For qualified investors only. We keep enquiry details for 12 months if they do not lead to a relationship. See our Privacy Notice at algotoria.com/privacy.

Why Algotoria, and how do I choose between Classic Diversified and Classic Stable?

Algotoria is a BVI-licensed Approved Investment Manager (Certificate IBR/AIM/25/2214) running a fully systematic long–short programme in liquid cryptocurrency perpetual futures since October 2023. Four properties set us apart from a typical crypto manager:

  • Non-custodial. Every client funds a Separately Managed Account in their own name at Binance, OKX or Bybit. Algotoria holds a trade-only API key — never custody, never withdrawal rights. An exchange failure hurts you; an Algotoria failure cannot move your assets.
  • Performance-only fees. Zero management fee, zero entry fee, no lock-in. We charge a 25–30% quarterly success fee against a rolling high-water mark — and we charge nothing until prior losses are recovered. The co-founders run roughly $2.47 M of their own capital in the same strategies under the same terms.
  • Independently verifiable. The live track record is streamed to TradeLink Passport via a read-only exchange API. Every figure on this site is reproducible from data we do not control.
  • AI-native operating model. The trading signals are rules-based and Investment Committee–approved; AI is not used in trading decisions. But every operational function — compliance, risk reporting, investor support, software development — runs through AI-assisted workflows under human-in-the-loop oversight. That keeps the cost base lean and structurally supports the 0% management fee.

Algotoria Classic, the live family, offers two strategies, both running the same algorithmic engine and the same trend-following / counter-trend mix — 66% / 34% as at 31 August 2026, reset each quarter by the Investment Committee within a 50–100% / 0–50% range according to the market regime — across 10 to 50 uncorrelated sub-strategies on BTC, ETH and liquid altcoin perpetual futures (a mandate of up to 40 instruments; 11 in the current book).

Algotoria also runs a second, next-generation family, Algotoria Spike, which is pre-production and simulated; see What is Algotoria Spike? below.

  • Algotoria Classic Diversified — collateral is BTC, approved stablecoins and RWAs, managed by Algotoria. Target gross CAGR above 120% at the 35% drawdown budget, target Calmar above 3.5, budget customisable between 15% and 35%.
  • Algotoria Classic Stable — collateral is approved stablecoins, including USDT, USDC, RLUSD, OKUSD and USDG. Target gross CAGR above 90% at the 30% drawdown budget, target Calmar above 3.0, budget customisable between 10% and 30%. For stablecoins other than USDT, the account may borrow USDT against them to open USDT-margined perpetual positions, and the borrowed USDT accrues interest at the exchange’s rate, borne by the account; yield-bearing stablecoins (RLUSD, OKUSD, USDG) typically earn more than this cost. USDT collateral carries no such cost.

The minimum allocation is the same for both ($50 k / $100 k / $150 k by risk tier). Both use the NAV-based method for the success fee (AMA §1.1.18(a)); the Isolated USDT method (§1.1.18(b)) applies only to Custom-Collateral accounts. See the side-by-side comparison on the Classic Family before you choose.

How is performance measured? Why does my exchange dashboard show a different number?

Daily time-weighted returns (TWR) with compounding, computed from the unrealised margin balance of each strategy's reference portfolio, denominated in USDT and rebased to 0.00% on 1 January 2024 for the public chart. TWR is the industry-standard methodology that eliminates the distortive effect of capital movements (deposits and withdrawals) on the percentage return. Exchange dashboards (OKX, Binance, Bybit) use simplified estimation methods that do not properly handle transfers, so their headline percentage will differ. The absolute dollar-denominated P&L on the exchange dashboard remains correct; only the percentage is affected.

How can I independently verify the live track record?

Via TradeLink Passport, which streams each strategy's reference portfolio through a read-only exchange API. Links to the Classic Diversified and Classic Stable portfolios are on the Classic Diversified and Classic Stable pages. On request, Algotoria will additionally provision read-only API keys to your designated auditor or verification platform, giving direct access to the full trade history and daily return series on the underlying exchange accounts — so you can reconstruct and verify every published metric without relying on firm-generated reports.

What is the fee structure, and how does the high-water mark work?

Zero management fee, zero entry fee. A quarterly performance fee of 25–30% (tiered by allocation size) on Net Trading Profits above a rolling high-water mark. Formula: P = E − MAX(B, HW) − I, where E is the ending balance, B is the starting balance, HW is the rolling high-water mark, and I is net inflows/outflows. If the account falls below the HWM, no fees are levied until the deficit is fully recovered through trading gains. Clawbacks are explicitly not applied. Classic Diversified and Classic Stable both use the NAV-based variant (AMA §1.1.18(a)); the Isolated USDT variant (§1.1.18(b)) applies only to Custom-Collateral accounts. Fee tiering is documented in Exhibit 1 of the Asset Management Agreement.

See the full due-diligence FAQ for 50+ additional questions.
Algotoria Limited is a BVI-regulated Approved Investment Manager under the Securities and Investment Business Act, 2010. The content on this page is informational and does not constitute an offer to sell securities or investment advice. Services are available to qualified investors only. Past performance is not indicative of future results.