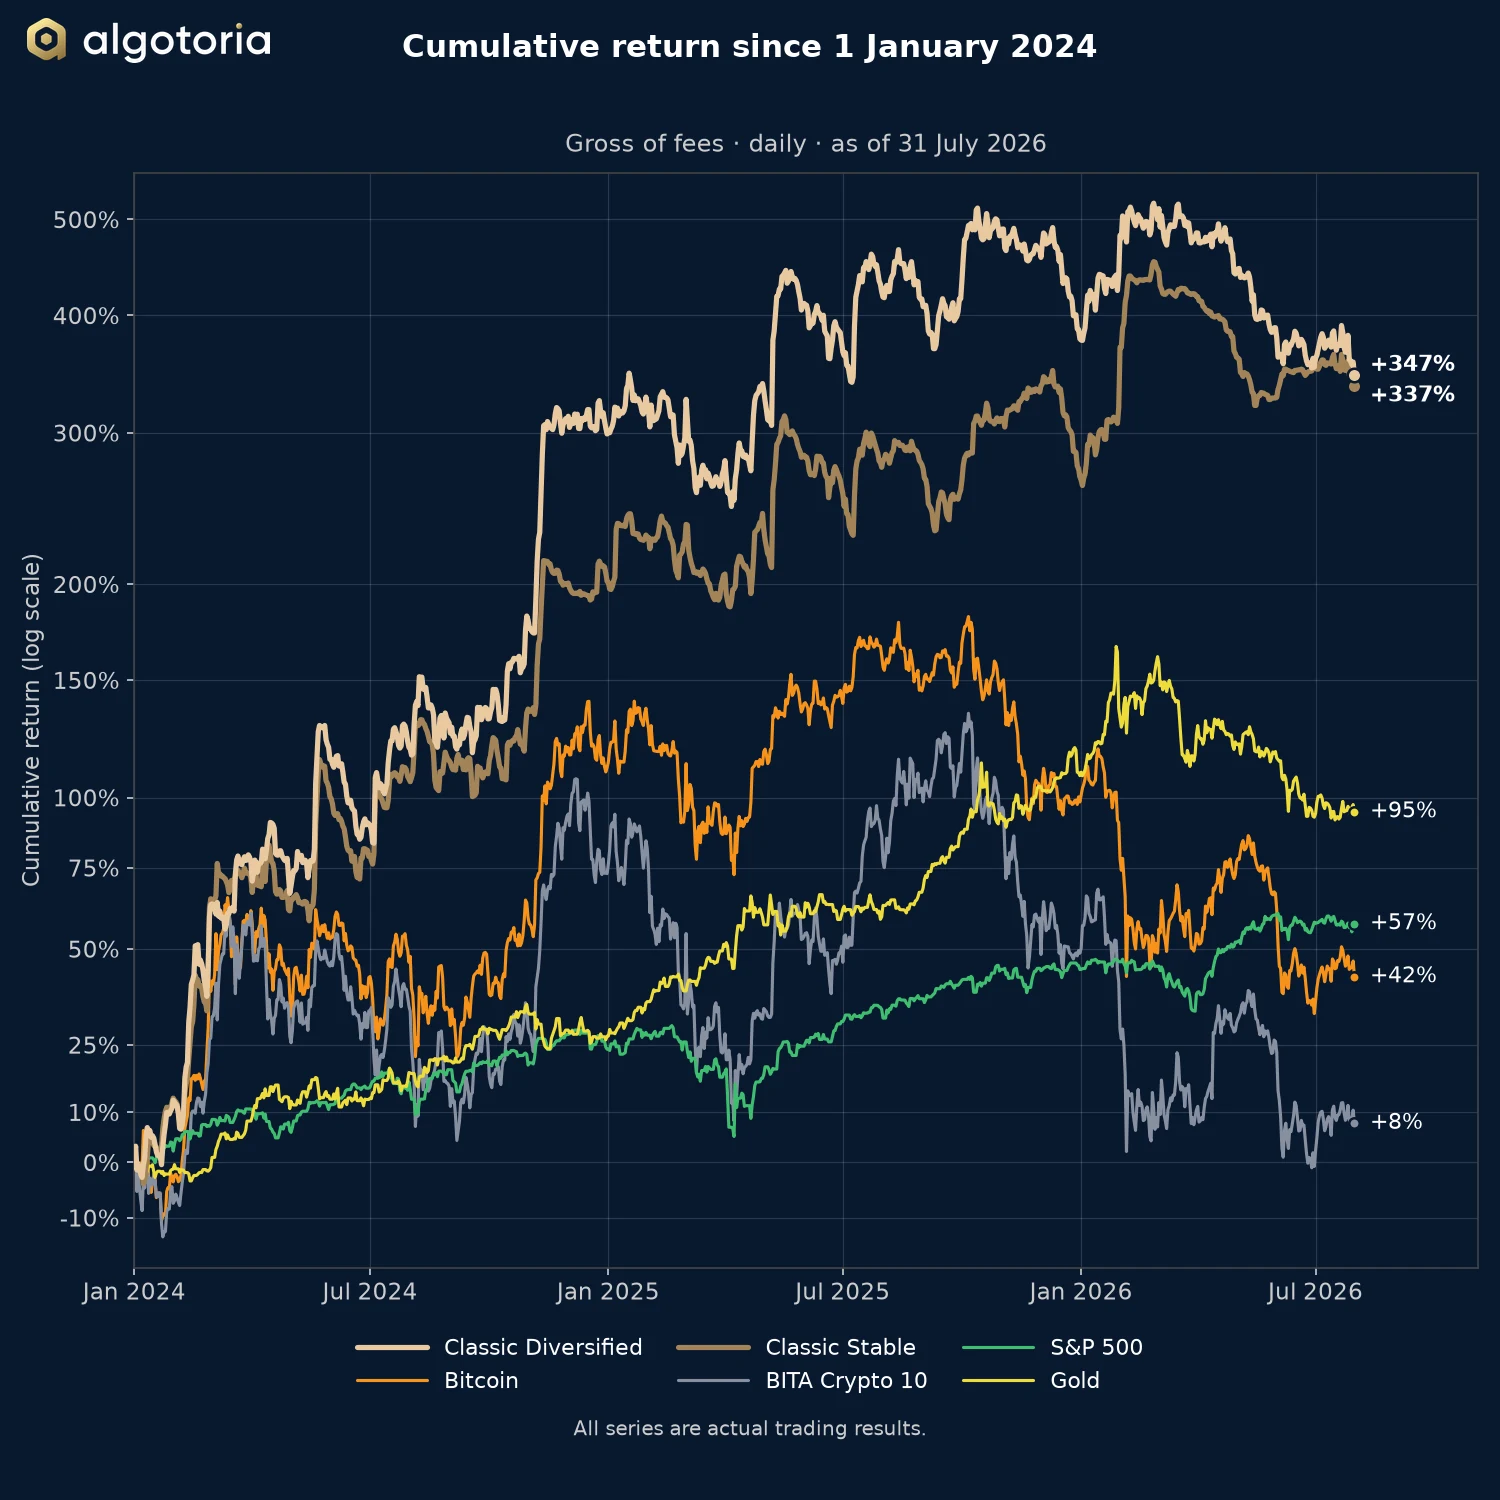
Both Classic strategies lost ground in July 2026. Classic Diversified returned −1.39% and Classic Stable −3.36%. For most of the month the crypto market traded in a narrow range without a sustained trend.
Performance
| July | Year to date | |||
|---|---|---|---|---|
| Gross | Net 25% | Gross | Net 25% | |
| Classic Diversified | −1.39% | −1.39% | −6.57% | −9.33% |
| Classic Stable | −3.36% | −3.36% | +18.76% | +9.60% |
| 12 months | Since 1 January 2024 | ||
|---|---|---|---|
| Gross | Net 25% | Gross | |
| Classic Diversified | −14.55% | −18.65% | +347% |
| Classic Stable | +16.62% | +7.63% | +337% |
Portfolio manager’s comment
Why recent results have been weak
The past few months have been difficult for both strategies. The main reason is the nature of the market itself. For most of July the crypto market stayed in a narrow trading range with no sustained direction.
Such conditions are among the most challenging for trend-following strategies. Frequent reversals and the lack of strong momentum prevent the algorithms from realising their potential.
Bitcoin’s volatility index is currently low. Historically, periods of very low volatility have rarely lasted long. They have usually ended in a sharp rise in volatility and a strong directional move. A similar environment occurred in January 2026, when Classic Stable returned +27.91% and Classic Diversified +21.73%.
The longer record
Algorithmic strategies should be judged over longer horizons, not by the results of a few months. Since 1 January 2024, Classic Diversified has returned +347% and Classic Stable +337%, with reinvestment and before performance fees.
The second quarter ended with a loss for both strategies. On the published track since 1 January 2024, every losing quarter has been followed by a profitable one. This is a record of past quarters. It does not indicate the result of the current one.
Developing the portfolio
The investment team does not simply wait for the market phase to change. It continues to expand the portfolio by adding long-only and counter-trend models, testing strategies based on neural networks and broadening the range of trading models. The aim is to reduce the dependence of results on a single market regime.
The team also monitors whether the market characteristics underlying its models remain intact. At present it has found no evidence that they have deteriorated. The market appears to be in a prolonged phase that has historically been among the most difficult for trend-following strategies.
It is impossible to say when this phase will end. Extended periods of low volatility have often been followed by the strongest directional moves, and these are the conditions in which the strategies have historically performed best. This describes past behaviour. It is not a forecast.