Performance reports

Monthly report: September 2026 and third quarter

2 October 2026 · By Evgenii Voronchikhin

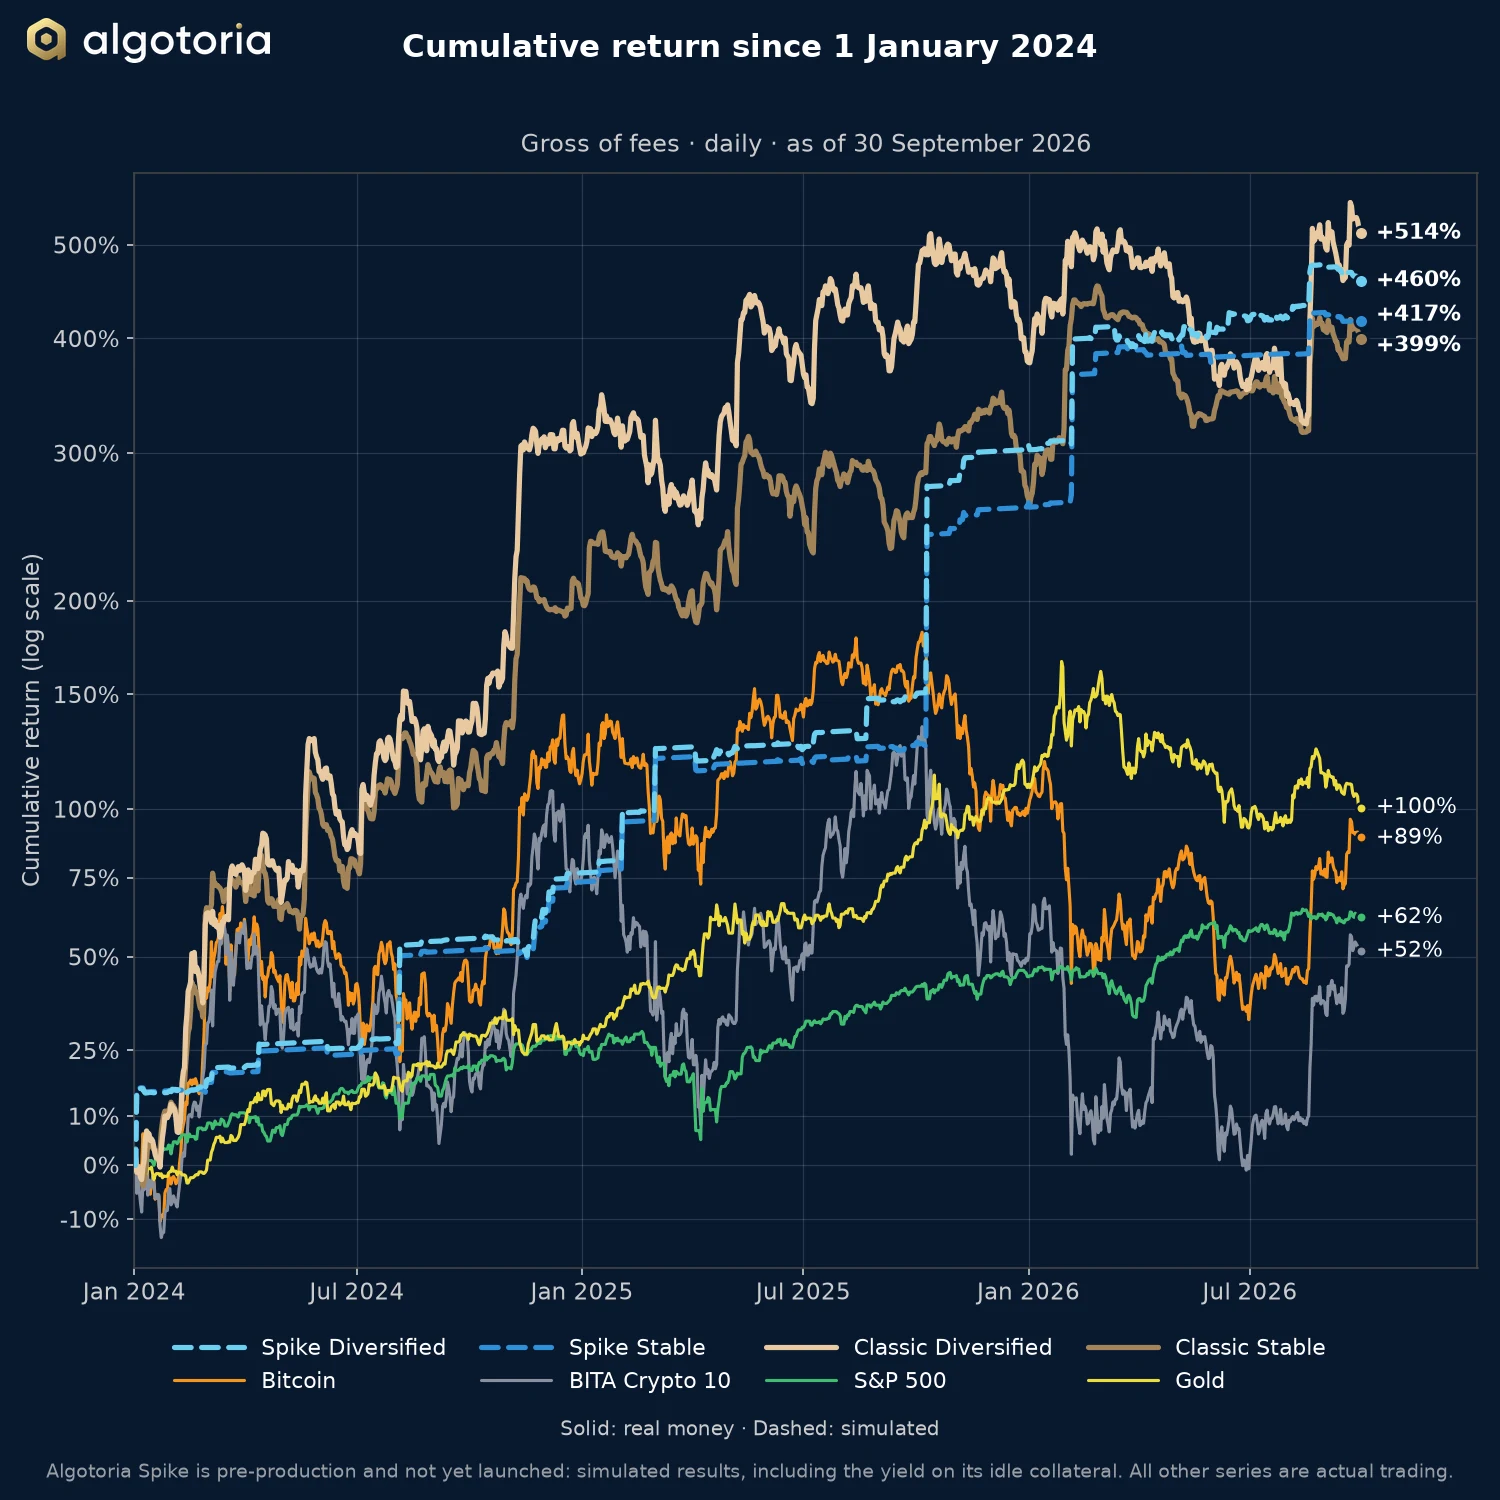
Line chart of cumulative return since 1 January 2024 for Spike Diversified, Spike Stable, Classic Diversified and Classic Stable against Bitcoin, BITA Crypto 10, the S&P 500 and gold, as of 30 September 2026.
Cumulative return since 1 January 2024, gross of fees, as of 30 September 2026. Logarithmic scale.

The third quarter of 2026 ended in profit for both Classic strategies: Classic Diversified returned +35.46% and Classic Stable +10.40%. September itself finished close to zero, with Classic Diversified at +1.45% and Classic Stable at −2.09%.

Performance

September 2026 and year to date
SeptemberYear to date
GrossNet 25%GrossNet 25%
Spike Diversified (simulated) −3.03%−3.03%+39.00%+18.70%
Spike Stable (simulated) −1.71%−1.71%+43.55%+21.72%
Classic Diversified +1.45%+1.45%+28.33%+24.54%
Classic Stable −2.09%−2.09%+35.67%+25.21%
Longer periods
12 monthsSince 1 January 2024
GrossNet 25%Gross
Spike Diversified (simulated) +124.89%+87.59%+460%
Spike Stable (simulated) +128.43%+92.65%+417%
Classic Diversified +18.93%+13.22%+514%
Classic Stable +39.10%+28.37%+399%
Returns to 30 September 2026. Spike Diversified and Spike Stable are simulated.

Portfolio manager’s comment

The third quarter ended in profit for both Classic strategies. The second quarter had been a loss for both. Since 1 January 2024, neither Classic strategy has recorded two negative quarters in a row, on gross or on net 25% figures, and the third quarter kept that pattern.

Three different months

July continued the sideways market. Bitcoin traded in a narrow range of $60,000–66,000 for the whole month, and the volatility index stayed near multi-year lows. This is the hardest environment for trend-following algorithms. Classic Diversified returned −1.39% and Classic Stable −3.36%.

August brought the impulse. On 19 August the market broke out of its multi-month range, and about $3 billion of short positions were liquidated within a day. Buybacks of bonds by the US Treasury, a weaker dollar and expectations for the CLARITY Act, the US crypto-asset regulation bill, supported the move. The algorithms captured it: Classic Diversified returned +35.40% and Classic Stable +16.68%.

September brought sharp moves in both directions. On 15 September the US Senate failed to advance the CLARITY Act, with 49 votes against 50. On 16 September the Federal Reserve raised its rate by 25 basis points, the first increase in three years. Bitcoin fell towards $75,000, then reversed sharply to an eight-month high near $87,000, helped by the largest weekly inflow into spot ETFs of the year, about $2.4 billion. Even the $387 million hack of the Bitget exchange did not stop the rebound. Frequent reversals without a sustained trend are an awkward environment for trend-following systems, so September finished near zero: Classic Stable returned −2.09% and Classic Diversified +1.45%, helped by the bitcoin in its collateral.

Collateral

Algotoria raised the bitcoin share of the Classic Diversified collateral during the decline in spring and summer. In the third quarter this added materially to the return of the algorithms. After the latest rise, near $83,000, the collateral-management algorithm cut the bitcoin share to 30%, which locked in part of the gain.

The twelve months and Spike

The longer horizon matters more than any single quarter. In the twelve months to 30 September 2026 the crypto market went through a fall of more than 50%, a multi-month sideways phase and a sharp recovery. Over the same period Classic Stable returned +39.10% and Classic Diversified +18.93%, against −26.68% for Bitcoin and −27.75% for BITA Crypto 10. These figures are gross of performance fees.

The report also shows Spike, a new strategy based on neural networks. Over twelve months the simulated Spike Diversified returned +124.89% and Spike Stable +128.43%. These are simulations in forward testing, not returns on client funds. The outcome of the test will decide whether Spike is added to client portfolios.

The fourth quarter

Volatility has returned to the market, and it is the main condition for the algorithms. In the fourth quarter the investment team is watching the next steps of the Federal Reserve, the level of yields on long-dated US Treasuries, and the future of crypto-asset regulation in the United States after the CLARITY Act stalled. Each of these can produce a strong directional move, and the Classic algorithms can take long and short positions. In parallel, the team continues to widen the portfolio with countertrend and long-only algorithms.

Get Started

Typical onboarding takes one business day, plus the international bank transfer if you fund from fiat.

Start a conversation

Tell us a little about yourself and a co-founder will reply within one business day.

By submitting, you agree we may contact you at the details above. We do not share your data with third parties. For qualified investors only. We keep enquiry details for 12 months if they do not lead to a relationship. See our Privacy Notice at algotoria.com/privacy.

How is performance measured? Why does my exchange dashboard show a different number?

Daily time-weighted returns (TWR) with compounding, computed from the unrealised margin balance of each strategy's reference portfolio, denominated in USDT and rebased to 0.00% on 1 January 2024 for the public chart. TWR is the industry-standard methodology that eliminates the distortive effect of capital movements (deposits and withdrawals) on the percentage return. Exchange dashboards (OKX, Binance, Bybit) use simplified estimation methods that do not properly handle transfers, so their headline percentage will differ. The absolute dollar-denominated P&L on the exchange dashboard remains correct; only the percentage is affected.

What is the fee structure, and how does the high-water mark work?

Zero management fee, zero entry fee. A quarterly performance fee of 25–30% (tiered by allocation size) on Net Trading Profits above a rolling high-water mark. Formula: P = E − MAX(B, HW) − I, where E is the ending balance, B is the starting balance, HW is the rolling high-water mark, and I is net inflows/outflows. If the account falls below the HWM, no fees are levied until the deficit is fully recovered through trading gains. Clawbacks are explicitly not applied. Classic Diversified and Classic Stable both use the NAV-based variant (AMA §1.1.18(a)); the Isolated USDT variant (§1.1.18(b)) applies only to Custom-Collateral accounts. Fee tiering is documented in Exhibit 1 of the Asset Management Agreement.

How can I independently verify the live track record?

Via TradeLink Passport, which streams each strategy's reference portfolio through a read-only exchange API. Links to the Classic Diversified and Classic Stable portfolios are on the Classic Diversified and Classic Stable pages. On request, Algotoria will additionally provision read-only API keys to your designated auditor or verification platform, giving direct access to the full trade history and daily return series on the underlying exchange accounts — so you can reconstruct and verify every published metric without relying on firm-generated reports.

What drawdowns should I realistically expect?

Typical annual drawdowns of 20–25% on Algotoria Classic Stable, 15–30% on Algotoria Classic Diversified. Historical back-tests reached 30%. Drawdowns beyond these ranges trigger a formal Investment Committee review.

All drawdown figures quoted on this site — and the agreed drawdown budget selected during onboarding — are measured on the gross trading-account return curve, before deduction of Algotoria's quarterly performance fee. Net-of-fee drawdowns experienced by the investor are larger by construction. Worked example: for Algotoria Classic Stable over 2024-01-01 → 2026-09-30, the adjusted maximum drawdown is −24.7% gross, −30.2% net of a 25% fee, and −31.3% net of a 30% fee.

Why are the Algotoria Spike results simulated, and what does that mean?

Neither Algotoria Spike strategy has managed client money yet. Their records are replays of the Algotoria Spike signal, generated walk-forward, through the production trading engine on exchange candles, so they show how the design would have behaved, not what an investor earned.

A simulation is not a track record: future results will differ, often materially, and all capital committed can be lost. The collateral rule of Algotoria Spike Diversified was chosen on data within the simulation window, so its figures are a hypothesis. Only Algotoria Classic has a real-money track record. Read the Risk Disclosure Notice before allocating.

See the full due-diligence FAQ for 50+ additional questions.
Algotoria Limited is a BVI-regulated Approved Investment Manager under the Securities and Investment Business Act, 2010. The content on this page is informational and does not constitute an offer to sell securities or investment advice. Services are available to qualified investors only. Past performance is not indicative of future results.