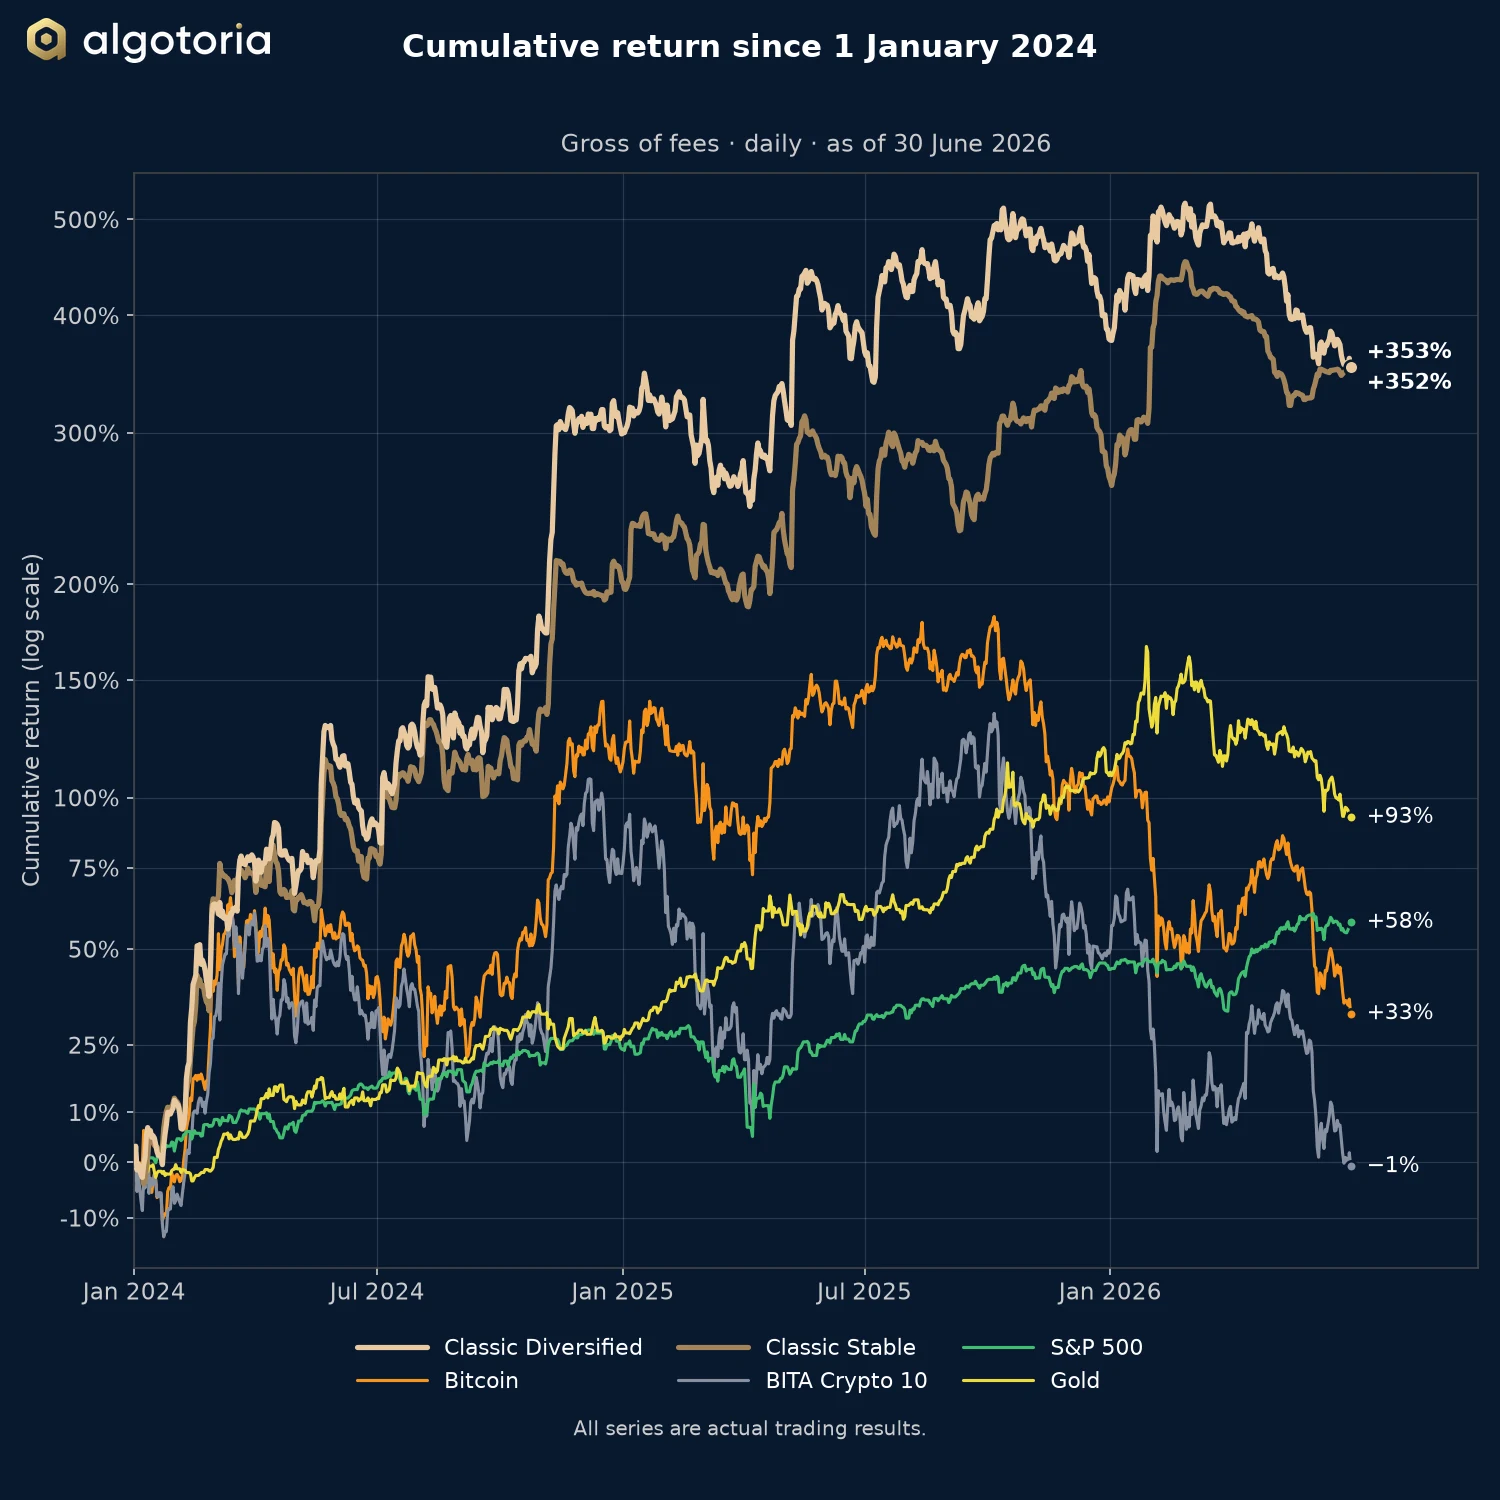
June was a turbulent month for crypto markets. Bitcoin returned −20.43% and the BITA Crypto 10 index −21.16%. Classic Stable returned +5.79%, and Classic Diversified −7.24%.
Performance
| June | Year to date | |||
|---|---|---|---|---|
| Gross | Net 25% | Gross | Net 25% | |
| Classic Diversified | −7.24% | −7.24% | −5.26% | −8.06% |
| Classic Stable | +5.79% | +5.79% | +22.89% | +13.42% |
| 12 months | Since 1 January 2024 | ||
|---|---|---|---|
| Gross | Net 25% | Gross | |
| Classic Diversified | −4.61% | −12.89% | +353% |
| Classic Stable | +25.40% | +11.24% | +352% |
Portfolio manager’s comment
Why Classic Stable returned less than in January and February
Investors asked a fair question. Bitcoin fell sharply in June, yet Classic Stable returned +5.79%. In January and February Bitcoin returned −23.59%, and Classic Stable returned +49.12%. The answer lies in the structure of the move.
In January and February the market fell fast, in one continuous impulse, with almost no meaningful retracements. These are near-ideal conditions for trend-following strategies. June looked different. The decline was slower and shallower, and it included more counter-moves. The first leg of the sell-off came at relatively low volatility, so the algorithms met more false breakouts and stop-losses than usual.
Trading logic and position sizing
The trading logic did not change. The investment team does not tune the algorithms by hand to the current market phase. That approach can flatter the results over a short stretch of history, but it weakens the strategy’s robustness over a long one.
The algorithms adapt automatically through position sizing. Leverage and position size increase when volatility is low and decrease when it is high. This keeps return and risk in balance over the long term.
Classic Diversified closed June in negative territory because the crypto-assets held as collateral fell in value. The fall also allows the strategy to build its Bitcoin position at lower prices over time.
The second quarter and the portfolio
Both strategies ended the second quarter with a loss: Classic Diversified −22.52% and Classic Stable −12.76%. On the published track since 1 January 2024, every losing quarter has been followed by a profitable one. This is a record of past quarters. It says nothing certain about the next.
The strategies trade both long and short, so they can profit from a continued decline or from a sharp rise. They do not depend on a forecast of the market’s direction. In June the investment team added two trend-following algorithms that trade long positions in XRP and BCH. It plans to raise the share of counter-trend algorithms: a long-only counter-trend strategy across the ten largest crypto-assets is being launched, and two more long counter-trend strategies are in testing.