Performance reports

Monthly report: September 2025

3 October 2025 · By Evgenii Voronchikhin

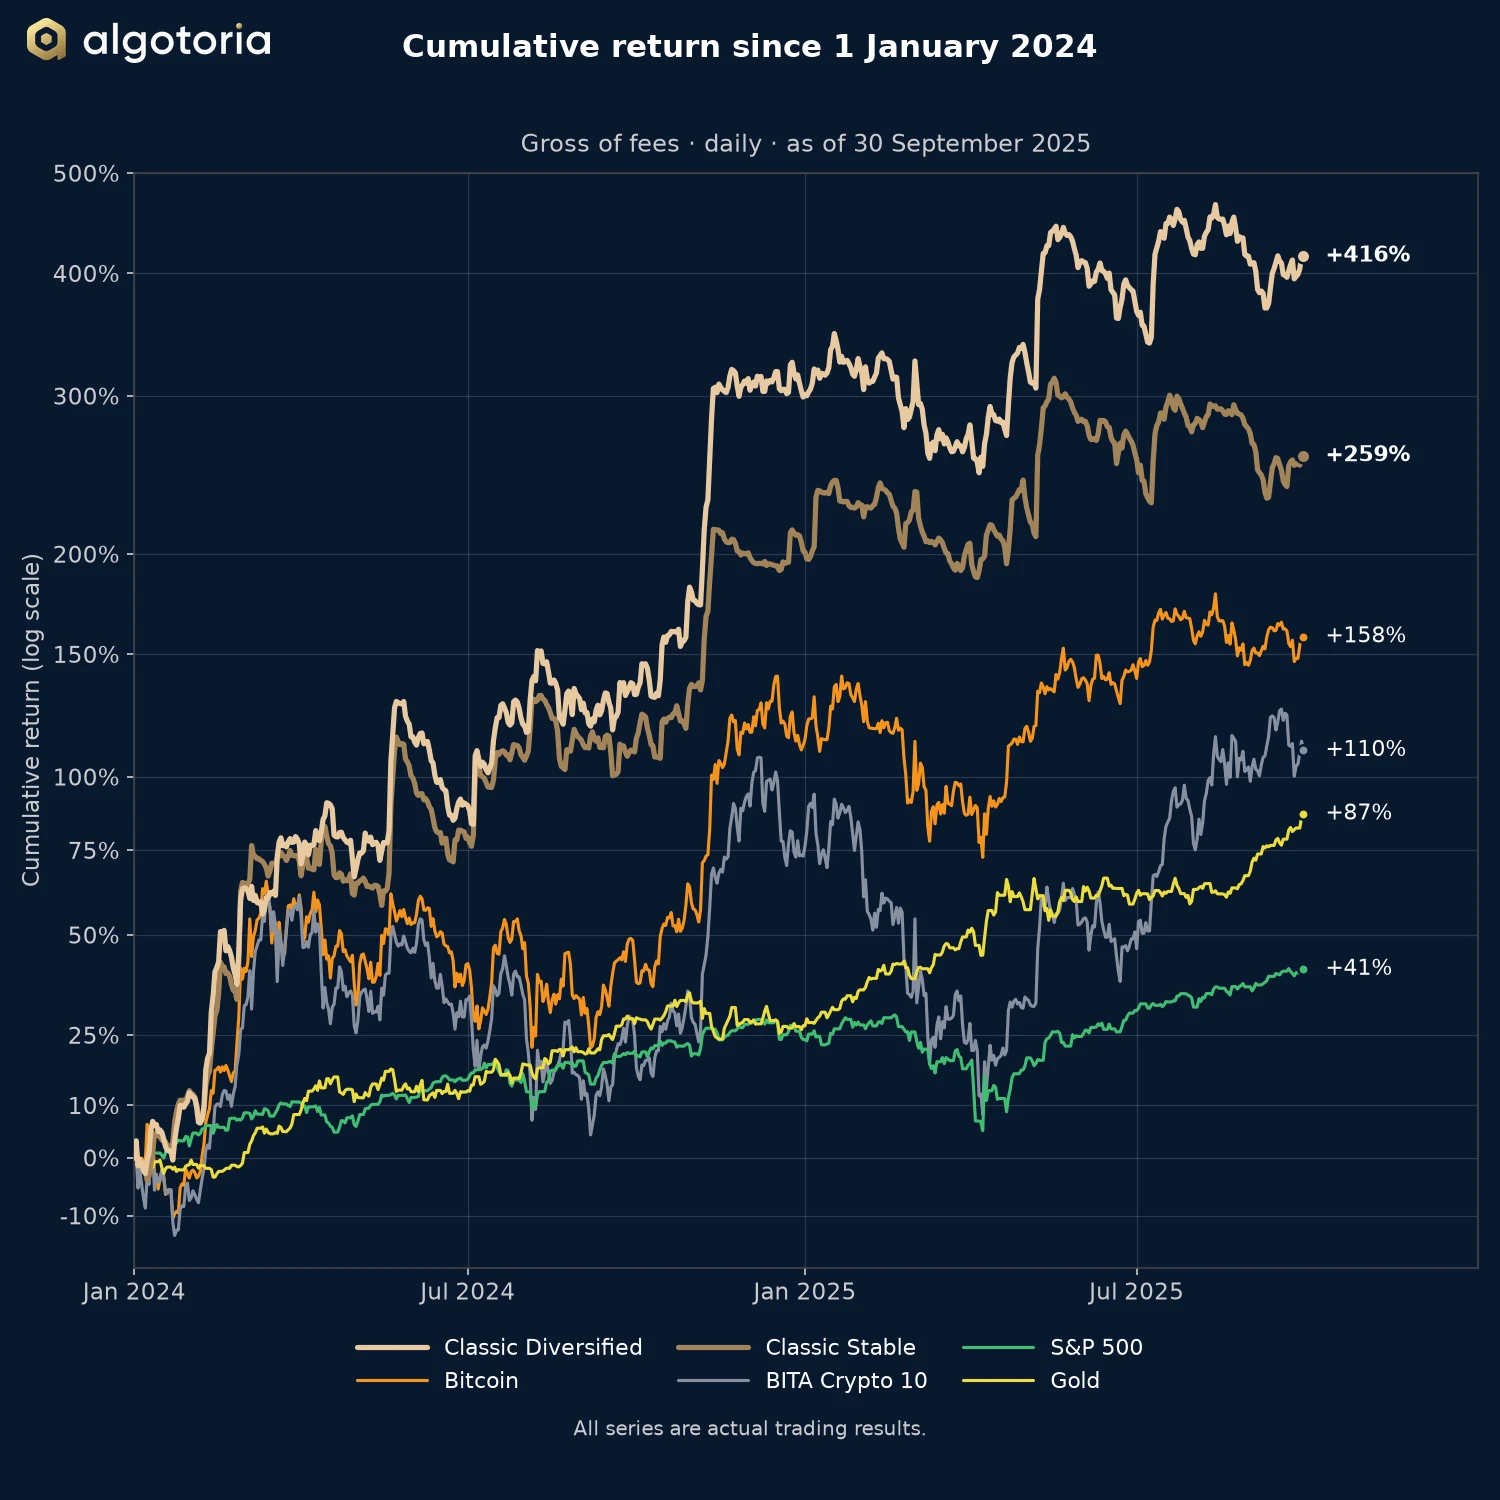
Line chart of cumulative return since 1 January 2024 for Classic Diversified and Classic Stable against Bitcoin, BITA Crypto 10, the S&P 500 and gold, as of 30 September 2025.
Cumulative return since 1 January 2024, gross of fees, as of 30 September 2025. Logarithmic scale.

September was a month of low volatility for crypto assets. Classic Diversified returned +0.05%, while Classic Stable returned −4.72%. A rising impulse in the first days of October recovered the September result of Classic Stable.

Performance

September 2025 and year to date
SeptemberYear to date
GrossNet 25%GrossNet 25%
Classic Diversified +0.05%+0.05%+29.30%+11.12%
Classic Stable −4.72%−4.72%+18.96%+5.24%
Longer periods
12 monthsSince 1 January 2024
GrossNet 25%Gross
Classic Diversified +122.22%+82.36%+416%
Classic Stable +71.50%+46.34%+259%
Returns to 30 September 2025.

Portfolio manager’s comment

Bitcoin spent September in a range of roughly $108,000 to $117,000 and returned +5.36% for the month. Volatility stayed low throughout, which does not suit trend-following algorithms.

Classic Stable ended September at −4.72%. Classic Diversified finished the month close to flat at +0.05%. It stayed ahead of Classic Stable mainly because part of its collateral is held in bitcoin, which rose over the month.

The picture changed in the first days of October. Bitcoin moved up with a strong impulse, and the trend algorithms earned from it. From the close of 30 September to the close of 3 October (UTC), Classic Stable returned +6.23% and Classic Diversified +11.88%.

Volatility and the portfolio

Bitcoin has kept rising slowly while volatility remains near its five-year lows. A breakout can begin at any moment, and a breakout is the environment in which the trend algorithms earn most.

The investment team is also launching one counter-trend strategy that opens positions from the long side. It is intended to smooth the portfolio’s return curve and its drawdowns, and so to reduce the portfolio’s dependence on strong trends.

Get Started

Typical onboarding takes one business day, plus the international bank transfer if you fund from fiat.

Start a conversation

Tell us a little about yourself and a co-founder will reply within one business day.

By submitting, you agree we may contact you at the details above. We do not share your data with third parties. For qualified investors only. We keep enquiry details for 12 months if they do not lead to a relationship. See our Privacy Notice at algotoria.com/privacy.

How is performance measured? Why does my exchange dashboard show a different number?

Daily time-weighted returns (TWR) with compounding, computed from the unrealised margin balance of each strategy's reference portfolio, denominated in USDT and rebased to 0.00% on 1 January 2024 for the public chart. TWR is the industry-standard methodology that eliminates the distortive effect of capital movements (deposits and withdrawals) on the percentage return. Exchange dashboards (OKX, Binance, Bybit) use simplified estimation methods that do not properly handle transfers, so their headline percentage will differ. The absolute dollar-denominated P&L on the exchange dashboard remains correct; only the percentage is affected.

What is the fee structure, and how does the high-water mark work?

Zero management fee, zero entry fee. A quarterly performance fee of 25–30% (tiered by allocation size) on Net Trading Profits above a rolling high-water mark. Formula: P = E − MAX(B, HW) − I, where E is the ending balance, B is the starting balance, HW is the rolling high-water mark, and I is net inflows/outflows. If the account falls below the HWM, no fees are levied until the deficit is fully recovered through trading gains. Clawbacks are explicitly not applied. Classic Diversified and Classic Stable both use the NAV-based variant (AMA §1.1.18(a)); the Isolated USDT variant (§1.1.18(b)) applies only to Custom-Collateral accounts. Fee tiering is documented in Exhibit 1 of the Asset Management Agreement.

How can I independently verify the live track record?

Via TradeLink Passport, which streams each strategy's reference portfolio through a read-only exchange API. Links to the Classic Diversified and Classic Stable portfolios are on the Classic Diversified and Classic Stable pages. On request, Algotoria will additionally provision read-only API keys to your designated auditor or verification platform, giving direct access to the full trade history and daily return series on the underlying exchange accounts — so you can reconstruct and verify every published metric without relying on firm-generated reports.

What drawdowns should I realistically expect?

Typical annual drawdowns of 20–25% on Algotoria Classic Stable, 15–30% on Algotoria Classic Diversified. Historical back-tests reached 30%. Drawdowns beyond these ranges trigger a formal Investment Committee review.

All drawdown figures quoted on this site — and the agreed drawdown budget selected during onboarding — are measured on the gross trading-account return curve, before deduction of Algotoria's quarterly performance fee. Net-of-fee drawdowns experienced by the investor are larger by construction. Worked example: for Algotoria Classic Stable over 2024-01-01 → 2026-09-30, the adjusted maximum drawdown is −24.7% gross, −30.2% net of a 25% fee, and −31.3% net of a 30% fee.

See the full due-diligence FAQ for 50+ additional questions.
Algotoria Limited is a BVI-regulated Approved Investment Manager under the Securities and Investment Business Act, 2010. The content on this page is informational and does not constitute an offer to sell securities or investment advice. Services are available to qualified investors only. Past performance is not indicative of future results.